
Industrial Distribution M&A Multiples Report 2026: Valuation Benchmarks by Size and Category
Industrial distribution M&A in 2026 is led by strategic buyers: they closed nearly 89% of distribution deals in Q3 2025 (PMCF), and disclosed deals such as DNOW/MRC Global and Applied/Hydradyne priced at 9.4x to 9.6x EBITDA.
Key takeaways
- PMCF counted 138 distribution deals closed worldwide in Q3 2025; strategic acquirers completed 123 of them, and more than 90% of US deals (PMCF Q3 2025 Pulse).
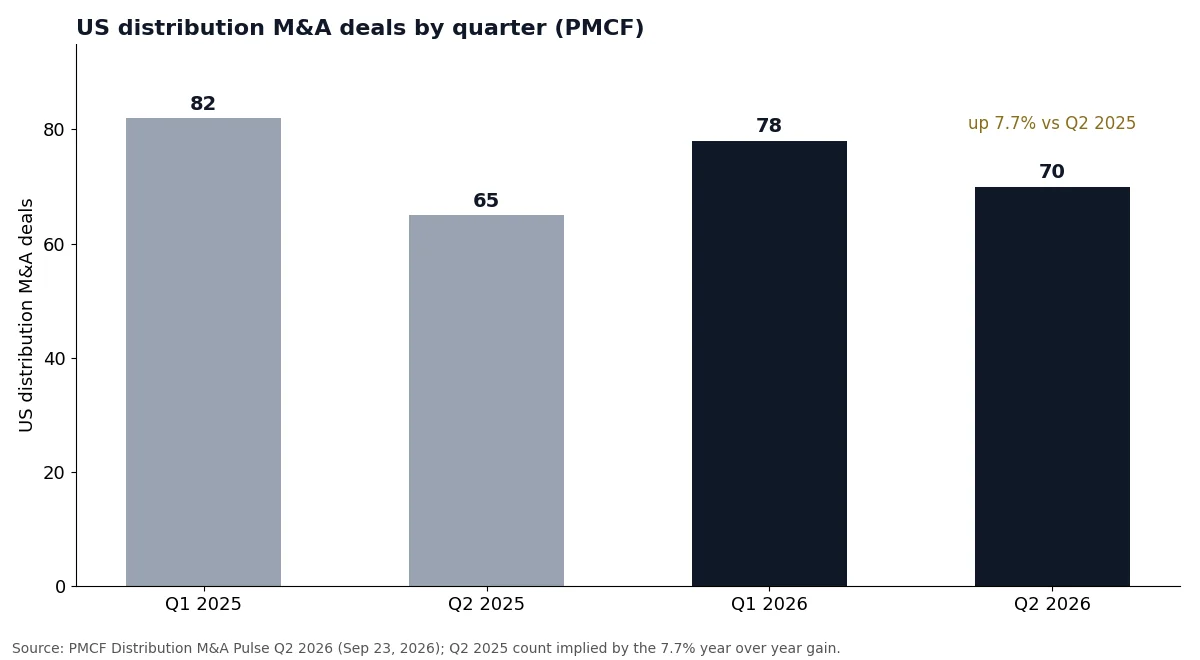
- US volume held up into 2026: 78 announced deals in Q1 2026 against 82 a year earlier, and 70 in Q2 2026, up 7.7% (PMCF Q2 2026 Pulse).
- Applied Industrial paid $282.1M for fluid power distributor Hydradyne, which it expects to add $260M of sales and $30M of EBITDA: 9.4x EBITDA (Applied 10-K FY2025).
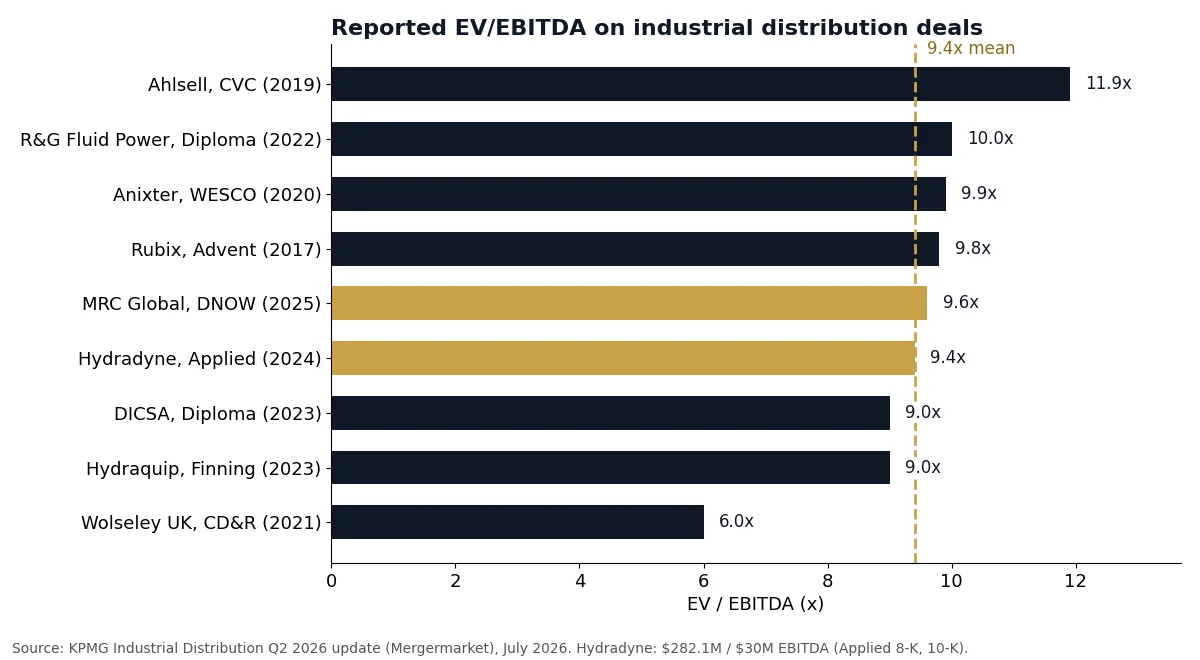
- KPMG’s list of disclosed distribution deals runs from 6.0x to 11.9x EBITDA with a 9.4x mean; DNOW’s purchase of MRC Global is reported at 9.6x (KPMG, July 2026).
- Public industrial, MRO and safety distributors traded at a 17.7x median EV/EBITDA on June 30, 2026, against a 10.3x long-run average (KPMG, S&P Capital IQ data).
Thinking about selling your distribution business?
A 15-minute confidential call shows you which consolidators and PE platforms would compete for your line card, and a likely valuation range. No cost, no obligation.
Smaller wholesalers priced on SDE, and the inventory and working capital terms that change their checks, are covered in our wholesale business valuation guide.
Automation distributor deals such as Tavoron, Galco and Sonepar are tracked alongside integrator deals in our industrial automation M&A buyer log.
Who is buying industrial distributors in 2026?
Strategic distributors buy most industrial distribution companies. PMCF’s Q4 2025 Pulse put strategics at about 85% of deals, and its Q3 2025 report at nearly 89%. Private equity enters mainly through platforms that then make add-ons, so a founder-led MRO, PVF, fluid power or electrical distributor usually meets two buyer types: a public or PE-backed consolidator, and a sponsor building a platform.
| Buyer group | Named examples (2024 to 2026) | What they pay for | Source |
|---|---|---|---|
| Public MRO and industrial consolidators | Applied Industrial Technologies, DXP Enterprises, DNOW, MSC Industrial, Core & Main | Territory, technical service, supplier lines they lack | Company 8-Ks and releases (deal ledger below) |
| Home improvement and building products platforms | The Home Depot via SRS Distribution, Lowe’s, QXO | Pro customer access; HVAC, roofing and interior products | Home Depot, Lowe’s and QXO releases |
| PE-controlled roll-ups | Distribution Solutions Group (LKCM Headwater, about 79% owner) | MRO, fastener and test equipment add-ons | Distribution Strategy Group, Jul 2026 |
| European strategics buying in North America and Europe | Diploma, Rexel, Atlas Copco, Beijer Alma | Fluid power, electrical and compressed air niches | KPMG Q2 2026 deal list |
A strategic is the most likely winner, but a sponsor platform often sets the top of the range because it prices your earnings plus future add-ons. Reach both groups in one process; our guide to selling an industrial distribution business covers how it runs.
Which industrial distribution acquisitions closed in 2024 to 2026?
The table lists 2024 to 2026 industrial distribution acquisitions with dates, owners and terms taken from the buyer’s own filing or release. Most add-ons are undisclosed; where a price and an earnings figure are both public, the implied multiple is shown with its arithmetic. Building products deals are included because those buyers now bid for HVAC and PVF distributors.
| Date (closed or announced) | Acquirer | Target and segment | Disclosed terms | Implied multiple |
|---|---|---|---|---|
| Dec 31, 2024 (closed) | Applied Industrial Technologies | Hydradyne, fluid power, Dallas | $282.1M; $260M sales and $30M EBITDA expected (8-K) | 9.4x EBITDA; 1.09x sales |
| Apr 29, 2025 (closed) | QXO | Beacon Roofing Supply, roofing distribution | $124.35 per share, about $11B (QXO) | Not disclosed |
| May 1, 2025 (closed) | Applied Industrial Technologies | IRIS Factory Automation, automation, Aurora, Illinois | $14.7M (Applied) | Not disclosed |
| Sep 4, 2025 (closed) | The Home Depot via SRS | GMS, wallboard and ceilings distribution | $110 per share, about $5.5B incl. net debt (Home Depot) | Not disclosed |
| Sep 2025 (agreed) | Core & Main | Canada Waterworks, waterworks, 3 Ontario branches | Asset purchase (Core & Main) | Not disclosed |
| Oct 9, 2025 (closed) | Lowe’s | Foundation Building Materials, 370+ locations | $8.8B cash (Lowe’s) | Not disclosed |
| Nov 6, 2025 (closed) | DNOW | MRC Global, PVF | All stock, about $1.5B incl. net debt (MDM) | 9.6x EBITDA (KPMG) |
| May 11, 2026 (closed) | The Home Depot via SRS | Mingledorff’s, HVAC, 42 locations | Not disclosed (Home Depot) | Not disclosed |
| Jun 17, 2026 (announced) | DXP Enterprises | General Repair Service, pumps, Minnesota | $12.2M LTM sales, $1.6M adjusted EBITDA (DXP) | Price not disclosed |
| Oct 13, 2026 (agreed) | Distribution Solutions Group | GradeEight (Winzer, FastServ Supply), MRO | About $110M annual sales (DSG coverage) | Not disclosed |
Two patterns stand out. Hydradyne and General Repair Service both carried EBITDA margins near 11% to 13% ($30M on $260M; $1.6M on $12.2M), and both buyers bought technical service capacity, not just a catalog. Home Depot alone closed GMS and Mingledorff’s within nine months.
What EBITDA multiples do industrial distributors sell for?
Disclosed industrial distribution deals cluster at 9x to 10x EBITDA: KPMG’s list of reported multiples has a 9.4x mean, and Hydradyne priced at 9.4x. Smaller private deals price lower. GF Data’s 2025 average for PE-backed distribution deals was 6.9x adjusted EBITDA, and BizBuySell’s sold wholesale and distribution businesses carry a 2.68x median earnings multiple.
| Size of distributor | Earnings basis | Benchmark | Source and date |
|---|---|---|---|
| Main Street (owner-run, under about $1M of earnings) | Seller’s discretionary earnings | 2.68x median; 2.00x to 3.44x middle half | BizBuySell, sold 2021 to 2025 |
| Lower middle market, $10M to $25M enterprise value | Adjusted EBITDA | 6.4x in Q3 2025, 5.7x in Q4 2025 (all industries) | GF Data via True North Mergers, Apr 2026 |
| PE-sponsored distribution deals, all sizes | Adjusted EBITDA | 6.9x average (2025); 7.2x all industries | GF Data; ACG release, Feb 18, 2026 |
| Disclosed strategic deals | EBITDA | 6.0x to 11.9x; 9.4x mean | KPMG Q2 2026 (Mergermarket data) |
| Public distributors (trading, not deal value) | LFY EBITDA | 17.7x median (MRO and safety); 13.2x (electrical) | KPMG, S&P Capital IQ, Jun 30, 2026 |
How do multiples differ by sub-segment?
Fluid power and MRO deals in KPMG’s list sit at 9.0x to 10.0x, PVF at 9.6x and electrical at 9.9x, while a construction-weighted plumbing and heating carve-out (Wolseley UK) priced at 6.0x. The one large-cap outlier is Ahlsell at 11.9x. Sub-segment matters less than margin and service content inside each deal.
| Sub-segment | Deal (date) | Acquirer | Reported EV/EBITDA |
|---|---|---|---|
| PVF | MRC Global (Nov 2025) | DNOW | 9.6x |
| Fluid power | Hydradyne (Dec 2024) | Applied Industrial | 9.4x (computed) |
| Fluid power | DICSA (Jul 2023) | Diploma | 9.0x |
| Fluid power | Hydraquip (Mar 2023) | Finning | 9.0x |
| Fluid power | R&G Fluid Power (Apr 2022) | Diploma | 10.0x |
| Electrical and wire | Anixter (Aug 2020) | WESCO | 9.9x |
| MRO | Rubix (May 2017) | Advent International | 9.8x |
| Plumbing and heating | Wolseley UK (Feb 2021) | CD&R | 6.0x |
| Broad industrial and building | Ahlsell (Feb 2019) | CVC | 11.9x |
Fluid power sellers can compare notes in our fluid power distribution sale guide, and electrical distributors in the wholesale electrical distribution guide.
Why can public consolidators pay more?
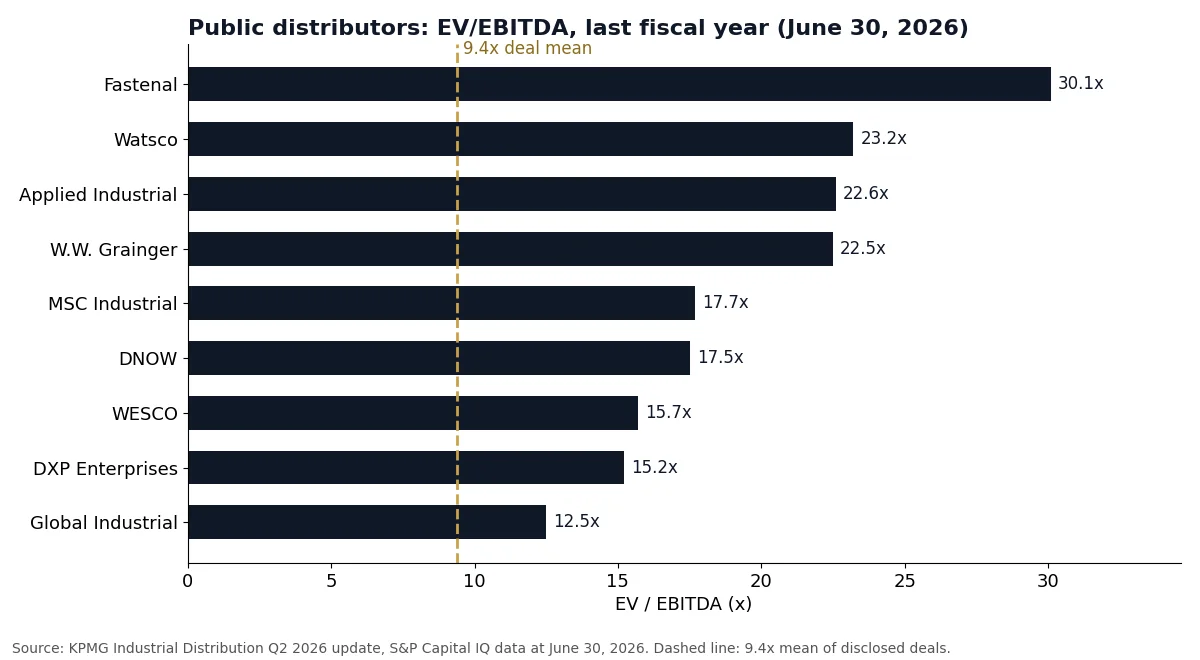
Public distributors trade well above what they pay. On June 30, 2026 Fastenal traded at 30.1x last-year EBITDA, Grainger at 22.5x and Applied Industrial at 22.6x, per KPMG. A buyer valued at 17.7x that pays 9.4x for a distributor adds value the moment the earnings join its own.
| Company | EV/EBITDA, last fiscal year | EV/EBITDA, next year |
|---|---|---|
| Fastenal | 30.1x | 26.7x |
| Watsco | 23.2x | 21.0x |
| Applied Industrial Technologies | 22.6x | 20.9x |
| W.W. Grainger | 22.5x | 19.9x |
| MSC Industrial Direct | 17.7x | 15.8x |
| DNOW | 17.5x | 13.4x |
| WESCO International | 15.7x | 13.0x |
| DXP Enterprises | 15.2x | 13.0x |
| Global Industrial | 12.5x | 12.8x |
| Worked example (illustrative) | Value |
|---|---|
| Distributor adjusted EBITDA | $3.0M |
| Price at 9.4x (KPMG mean of disclosed deals) | $28.2M |
| Same EBITDA valued at 17.7x (public MRO median) | $53.1M |
| Gap the public buyer captures | $24.9M |
That gap is the reason a competitive process matters. CT Acquisitions estimates (illustrative): a consolidator with branches in your metro can justify paying above the 9.4x mean and still capture most of the $24.9M gap; a single-bidder sale rarely sees that share.
What moves the multiple for a distributor?
Five items move an industrial distributor’s multiple most: gross margin and service content, line card exclusivity and whether suppliers will consent to a change of control, VMI and vending contracts, customer concentration, and inventory turns. Buyers price each one in diligence. The thresholds below are CT Acquisitions estimates (illustrative), not survey data.
| Driver | If your distributor shows | Expected buyer reaction | Evidence to prepare |
|---|---|---|---|
| Margin and service content | EBITDA margin near Hydradyne’s 11.5% or above, with repair or engineering revenue | Bids near or above the 9.4x mean | Gross margin by product line and service line, 3 years |
| Line card | Exclusive or protected territory lines from top 3 suppliers | Premium; strategics pay for lines they lack | Distributor agreements, change-of-control and assignment clauses |
| Supplier transferability | Agreements terminable on a change of control | Supplier consent becomes a closing condition | Written supplier sign-off plan before the LOI |
| VMI, vending, integrated supply | Signed multi-year VMI or vending contracts | Treated as recurring revenue | Contracts, renewal history, revenue per site |
| Customer concentration | One customer above 20% of sales | Discount, earnout or retention terms | Customer revenue by year, contract terms |
| Inventory turns | Turns well below peers, aged stock over 12 months | Inventory write-down before the peg is set | SKU aging report, last-sale dates |
Mingledorff’s is a useful line card case: Home Depot’s March 24, 2026 release describes it as a key Carrier and Bryant distributor, and that authorization is a large part of what a 42-branch HVAC buyer acquires. If your largest line can be cancelled on 30 or 90 days’ notice, ask your M&A counsel whether the supplier’s consent should be in hand before you sign an LOI.
Which buyer path fits your distributor?
Choose the buyer path by size of earnings and by how transferable your supplier lines are. The thresholds are CT Acquisitions estimates (illustrative), anchored to the GF Data, BizBuySell and KPMG benchmarks above.
| If your situation is | Then | Benchmark to test offers against |
|---|---|---|
| Under about $1M of SDE, owner runs sales | Run a Main Street sale to individuals and local competitors; expect SBA financing | BizBuySell 2.00x to 3.44x SDE |
| $1M to $3M of EBITDA, a general manager in place | Market to PE add-on buyers and regional strategics at the same time | GF Data 5.7x to 6.9x adjusted EBITDA |
| $3M+ of EBITDA with exclusive lines or service revenue | Include public consolidators and PE platforms in one process | KPMG 9.4x mean of disclosed deals |
| Top supplier can terminate on a change of control | Secure supplier consent before the LOI | Deal value at risk if consent is refused |
| Inventory turns below peers, aged stock | Write down or sell dead stock before you set the working capital peg | Peg tested against trailing 12 months |
What do buyers diligence in a distributor sale?
Buyers of distributors spend most diligence time on inventory, supplier rebates and the working capital peg, because all three move cash at closing. A quality of earnings review tests each one. These are the steps in the order buyers usually take them.
- Inventory count and aging: a physical count, a SKU aging report and an obsolescence reserve for stock with no sales in 12 to 24 months. If you use LIFO under 26 U.S.C. §472, ask your CPA how the LIFO reserve is taxed in an asset sale.
- Supplier rebates: buyers check whether volume rebates are earned on purchases in the trailing 12 months, how they are booked against cost of goods, and whether each program continues after closing.
- Supplier and customer consents: distributor agreements, VMI and vending contracts are read for change-of-control and assignment clauses.
- Working capital peg: usually set from a trailing 12-month average of net working capital; our working capital peg guide shows the method.
- Quality of earnings: normalized EBITDA, owner add-backs and rent on owner-held warehouses; see our quality of earnings page.
| Peg worked example (illustrative) | Value |
|---|---|
| Headline price | $28.2M |
| Working capital peg | $6.0M |
| Working capital delivered at closing | $5.4M |
| Price reduction (peg shortfall) | $600K |
Dead stock written off before the trailing 12-month peg window starts stays out of both the peg and the delivered figure, so it cannot create a shortfall like the $600K above.
How active is industrial distribution M&A right now?
US distribution M&A was steady to rising through mid-2026. PMCF counted 82 US deals in Q1 2025, 65 in Q2 2025, 78 in Q1 2026 and 70 in Q2 2026, a 7.7% year-over-year gain. Worldwide, closed deals fell from 149 in Q2 2025 to 138 in Q3 2025, and Q4 2025 was down 36% year over year.
| Quarter | US distribution deals | Worldwide closed deals | Source |
|---|---|---|---|
| Q1 2025 | 82 | n/a | PMCF Q2 2026 Pulse |
| Q2 2025 | 65 | 149 | PMCF Q4 2025 and Q2 2026 Pulses |
| Q3 2025 | n/a | 138 (123 by strategics) | PMCF Q3 2025 Pulse |
| Q4 2025 | n/a | Down 36% year over year | PMCF Q4 2025 Pulse |
| Q1 2026 | 78 | n/a | PMCF Q2 2026 Pulse |
| Q2 2026 | 70 | n/a | PMCF Q2 2026 Pulse |
Valuations rose with activity: KPMG’s industrial, MRO and safety index stood at 12.2x in June 2026 against a 10.3x long-run average, and the electrical index at 11.0x against 8.4x. For multiples across the wider industrial cluster, see the 2026 industrial and manufacturing M&A multiples report; for the sale process itself, see how to sell an industrial supply distributor.
How we compiled this
We compiled 21 named sources in November 2026: buyer 8-Ks, 10-Ks and press releases from Applied Industrial, DXP, QXO, Home Depot, Lowe’s, Grainger and Core & Main, four PMCF Distribution M&A Pulse reports, KPMG’s July 2026 industrial distribution update and the GF Data release on ACG. BizBuySell blocked automated access and GF Data tables are paid, so those figures come from search-result text and a broker summary. The July 2026 version of this page cited advisory reports we could not find; those figures were removed.
Frequently asked questions
What is considered industrial distribution?
Industrial distribution is the wholesale supply of products that factories, utilities and contractors use to run and maintain operations: MRO supplies, fasteners, PVF, fluid power, bearings, electrical and safety products. KPMG’s July 2026 update groups the public peers as industrial, MRO and safety (Grainger, Fastenal, MSC) and electronics and electrical (WESCO, Rexel).
What EBITDA multiple does an industrial distributor sell for?
Disclosed industrial distribution deals in KPMG’s July 2026 list range from 6.0x to 11.9x EBITDA with a 9.4x mean, and Applied Industrial paid 9.4x expected EBITDA for Hydradyne. PE-backed distribution deals averaged 6.9x adjusted EBITDA in 2025 per GF Data, and small owner-run wholesalers sold at a 2.68x SDE median on BizBuySell.
Who is the largest industrial distributor in the US?
By market value, W.W. Grainger was the largest US industrial MRO distributor in KPMG’s June 30, 2026 peer set at a market capitalization of about £48.4 billion, ahead of Fastenal at about £41.6 billion. Both trade above 22x last-year EBITDA, which explains why public consolidators can outbid private buyers.
What are some recent industrial distribution acquisitions?
Recent deals include Applied Industrial buying Hydradyne for $282.1M (December 31, 2024), DNOW combining with MRC Global for about $1.5B (November 6, 2025), Home Depot’s SRS buying Mingledorff’s (May 11, 2026), DXP buying General Repair Service (June 17, 2026) and DSG agreeing to buy Winzer’s parent GradeEight (October 13, 2026).
Do I need supplier consent to sell my distributorship?
Often yes, if your distributor agreements allow termination on a change of control or bar assignment. In an asset sale every agreement must be assigned. Ask counsel to list each top-10 supplier’s consent terms before marketing, because a refused authorization from a line like Carrier at Mingledorff’s can reprice the deal.
Sources
- PMCF, Distribution M&A Pulse Q3 2025 (Jan 7, 2026), accessed Nov 2026.
- PMCF, Distribution M&A Pulse Q4 2025 (Mar 9, 2026), accessed Nov 2026.
- PMCF, Distribution M&A Pulse Q2 2026 (Sep 23, 2026), accessed Nov 2026.
- KPMG UK, Industrial Distribution Q2 2026 industry update (July 2026), accessed Nov 2026.
- Applied Industrial Technologies, Form 10-K FY2025 and 8-K Exhibit 99.1 (Jan 2, 2025), accessed Nov 2026.
- Modern Distribution Management, DNOW completes MRC acquisition (Nov 2025), accessed Nov 2026.
- The Home Depot, SRS agreement to acquire Mingledorff’s (Mar 24, 2026), accessed Nov 2026.
- DXP Enterprises, General Repair Service release (Jun 17, 2026), accessed Nov 2026.
- ACG, GF Data Q4 2025 reports release (Feb 18, 2026), accessed Nov 2026.
- BizBuySell, wholesale and distribution valuation benchmark, search-result text, Nov 2026.
Related research: for the 2026 Industrial and Manufacturing M&A Multiples Report, the cluster pillar comparing 6 industrial sub-verticals side-by-side, see the linked report.
Related research: for the 2026 Metal Fabrication M&A Multiples Report, sibling industrial spoke covering manufacturing vs distribution dynamics, see the linked report.
