
Roofing M&A Multiples Report 2026: Valuation Benchmarks by Size and Segment
Roofing M&A multiples in 2026: published advisor benchmarks run from about 2.5x EBITDA for owner-run roofers to 9x for $7.5M+ EBITDA companies, but the priced roofing deals we could verify since 2021 all involve $400M+ revenue companies.
Key takeaways
- Auxo Capital Advisors puts roofing companies at 2.5x to 4.0x below $500K of adjusted EBITDA, 5.5x to 8.0x at $3.0M to $7.5M and 7.0x to 9.0x+ above $7.5M, and calls these directional, not appraisals (Auxo, June 4, 2026).
- Holcim paid USD 1.35 billion for Malarkey Roofing Products against USD 120 million of projected 2022 EBITDA, about 11.3x (Holcim, Dec 23, 2021); that is a shingle maker, not a contractor.
- FirstService paid $413 million for a controlling interest in Roofing Corp of America, a contractor with about $400 million of annual revenue, implying more than 1.0x revenue for 100% of the company (NRCA, Dec 20, 2023).
- Profitability Partners values storm and insurance revenue at 0.5x to 0.7x of the base multiple, so 40% storm revenue turns a 7x company into roughly 5.5x to 6x (Profitability Partners, updated Nov 8, 2026).
- Platforms bought 134 roofing contractors in 2024, up from 106 in 2023 (Roofing Contractor, Feb 20, 2025), yet none of those add-on releases states a price.
What multiples do roofing companies sell for in 2026?
Roofing companies sell for roughly 2.5x to 9x adjusted EBITDA in 2026 according to the advisors who publish ranges, with size doing most of the work: Auxo Capital Advisors moves from 2.5x to 4.0x below $500K of EBITDA to 7.0x to 9.0x+ above $7.5M. None of the four sources below names the deal dataset behind its numbers, so treat every row as one firm’s estimate.
| Source (date) | Size measure | Smallest band | Middle band | Largest band | Dataset named? |
|---|---|---|---|---|---|
| Auxo Capital Advisors (June 4, 2026) | Adjusted EBITDA | Under $500K: 2.5x to 4.0x | $1.5M to $3.0M: 4.5x to 6.5x; $3.0M to $7.5M: 5.5x to 8.0x | Above $7.5M: 7.0x to 9.0x+ | No |
| Profitability Partners (Mar 20, 2026, updated Nov 8, 2026) | Revenue | Under $3M: 3x to 5x | $3M to $10M: 5x to 7x | Above $10M with strong growth: 7x to 9x or higher | No |
| Lightning Path Partners (2026, undated) | Revenue | Under $1M: 2x to 3x | $3M to $7M: 4x to 5.5x | $15M+: 5x to 8x+ | No; a separate roofing line of 3x to 5x is credited to IBBA Market Pulse Q4 2023 |
| Peak Business Valuation (undated) | None (averages) | 2.47x to 3.55x EBITDA; 1.88x to 2.73x SDE; 0.33x to 0.51x revenue | No | ||
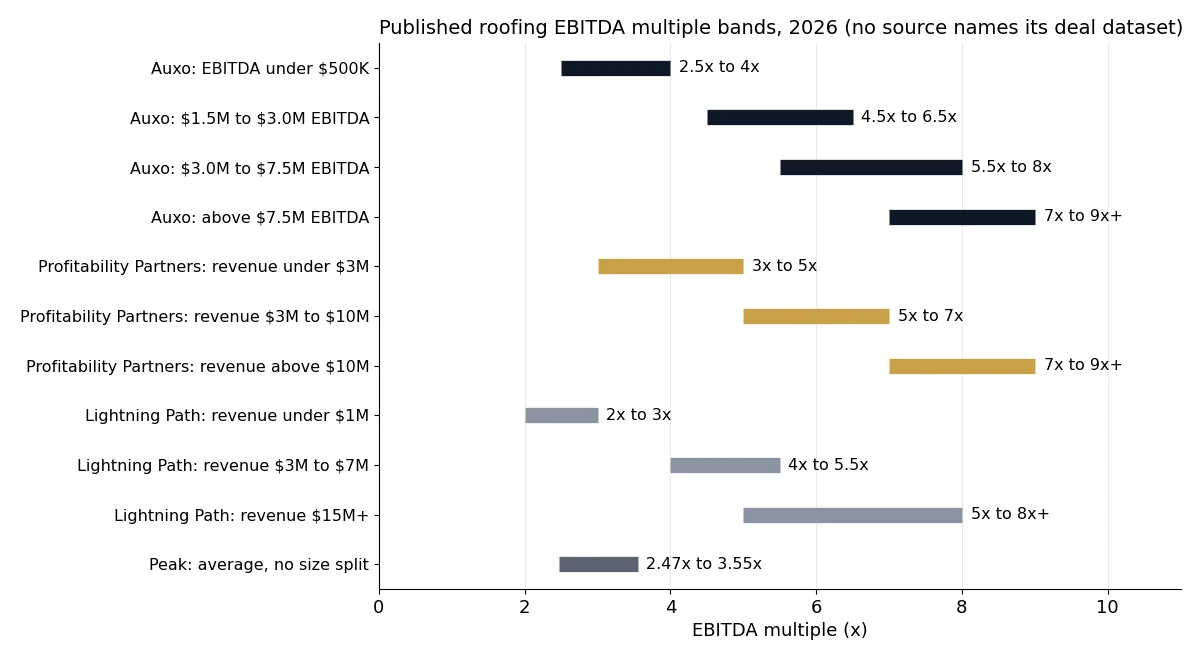
The bands overlap more than they agree. For a roofer with about $2M of adjusted EBITDA, Auxo implies 4.5x to 6.5x, Lightning Path’s size table 4.5x to 7x and Peak’s average 2.47x to 3.55x: a spread from $4.94M to $14M for the same company. The headline number a buyer quotes you will sit somewhere in that band; the deal terms decide where.
Two definitions explain part of the gap. Seller’s discretionary earnings (SDE) add the owner’s pay back to profit and apply to owner-run shops; adjusted EBITDA assumes a paid manager and applies once a company runs without the founder on the roof. Auxo switches from SDE to EBITDA between $500K and $1.5M of earnings, which is why its smallest band reads “EBITDA / SDE equivalent”.
Which roofing M&A deals disclosed a price?
Seven roofing transactions since 2021 have a public price: three manufacturers, two distributors and two contractors, one of them (Tecta America) a reported value rather than a closed deal. Three come with EBITDA, and their implied multiples cluster at 11.3x to 12.6x for businesses with $600 million or more of sales: the ceiling for roofing assets, not the price of an owner-run contractor.
| Deal (date) | Type | Price | Profit or sales base | Implied multiple (CT arithmetic) | Source |
|---|---|---|---|---|---|
| LafargeHolcim buys Firestone Building Products (Jan 7, 2021) | Commercial roofing manufacturer | USD 3.4 billion | 2020 (est.) EBITDA USD 270 million; net sales USD 1.8 billion | 12.6x EBITDA; 1.9x sales | Bridgestone Americas release |
| Holcim buys Malarkey Roofing Products (Dec 23, 2021) | Shingle manufacturer | USD 1.35 billion | Projected 2022 EBITDA USD 120 million; net sales USD 600 million | 11.3x EBITDA; 2.3x sales | Holcim release |
| Holcim completes Duro-Last (Apr 3, 2023) | Commercial roofing manufacturer | $1.29 billion | Pro forma net sales $540 million | 2.4x sales (no EBITDA stated) | Roofing Contractor |
| FirstService buys control of Roofing Corp of America (Dec 2023) | Commercial roofing contractor | $413 million for a controlling interest | Annual revenues about $400 million | Above 1.0x revenue for the whole company (stake size not disclosed) | NRCA Roofing News |
| Home Depot buys SRS Distribution (Mar 28, 2024) | Roofing-led distributor | About $18.25 billion enterprise value | Not stated in the release | Not computable from the release | Home Depot release |
| Tecta America, reported value (Nov 27, 2024) | Commercial roofing contractor | $3 billion to $4 billion (Bloomberg, not a closed deal) | 2023 revenue about $1.4 billion, self-reported | 2.1x to 2.9x revenue | Roofing Contractor |
| QXO buys Beacon Roofing Supply (closed Apr 29, 2025) | Roofing distributor | About $11 billion including debt ($124.35 per share) | 2024 Adjusted EBITDA $930.2 million; net sales $9.76 billion | 11.8x EBITDA; 1.1x sales | QXO; Beacon 8-K |
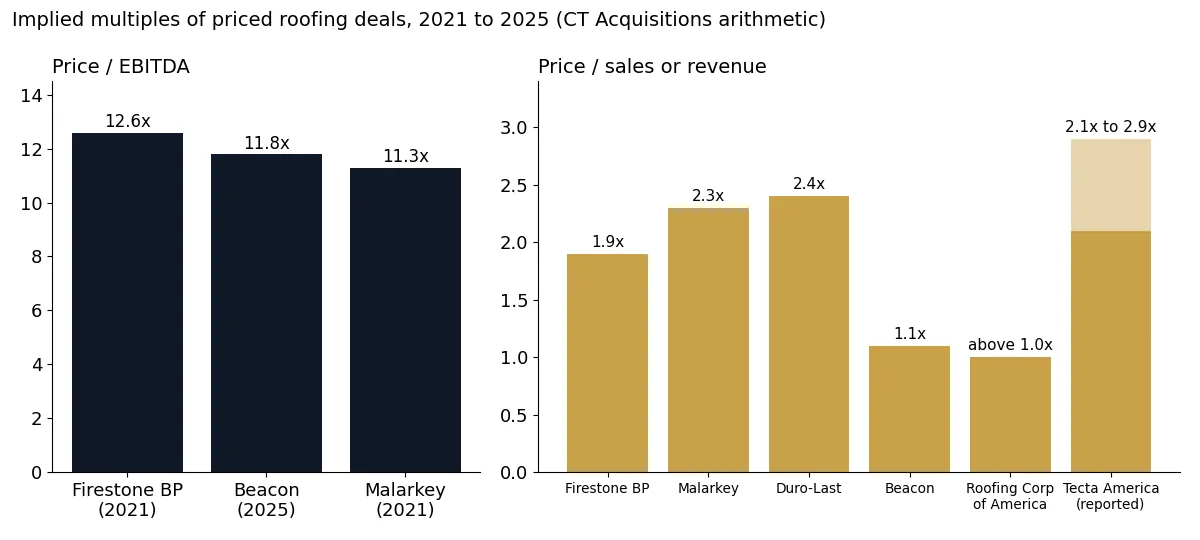
Synergies shrink these multiples for the buyer. Holcim expected USD 40 million a year of synergies from Malarkey; on USD 160 million of EBITDA plus synergies the price falls to 8.4x. An add-on roofer sold to a platform gets priced on its own EBITDA, while the platform books the synergy, which is one reason founders roll equity.
The two contractor rows are the closest public comparables for an owner. Roofing Corp of America ran 16 regional branches in 11 states with more than 900 professionals when FirstService bought control; its senior leadership kept the rest of the equity. Tecta America’s $3 billion to $4 billion is a reported range on a company with more than 100 locations (Tecta America, Oct 14, 2025), covered in our roofing private equity tracker.
Why do roofing multiple ranges disagree?
Roofing multiple ranges disagree because most of them cite no deals, and several pages credit numbers to reports that do not contain them. We checked six commonly repeated claims against the primary document; four do not hold up, including three errors on the July 2026 version of this page, which credited 9.0x to 13.0x platform multiples to PitchBook data we cannot verify.
| What several pages say | What the primary source says | Source |
|---|---|---|
| FMI and Hyde Park Capital publish roofing EBITDA multiple ranges | Hyde Park reports 53 transactions in 2024 versus 7 in 2018 and “upward movement on valuation multiples”, with no number; KPMG’s roofing update shows market size and about 6% top-three share, and its multiples table covers industrial sub-sectors. | Hyde Park Capital, Jul 8, 2025; KPMG Corporate Finance |
| Private equity buys a roofing platform every 48 hours | Roofing Contractor counts 134 contractors bought in 2024, one per 65 hours (8,760 / 134), mostly add-ons. | Roofing Contractor, Feb 20, 2025 |
| Roofing Corp of America is HGGC-backed (old version of this page) | Soundcore Capital Partners sold it; the deal closed December 15, 2023, and FirstService, a public company, now holds control. | Roofing Contractor, Dec 18, 2023 |
| Erie Home is owned by SVP Capital (old version of this page) | Gridiron partnered with Erie in 2021 and keeps the majority after Leaf Home acquired Erie Home. | PR Newswire, Sep 8, 2025 |
| Beacon Roofing Supply trades at 9x to 11x EBITDA in Q2 2026 (old version of this page) | Beacon stopped trading on April 29, 2025, when QXO completed the purchase. | QXO, Apr 29, 2025 |
| Precedent roofing tables show deal multiples | DAVCAP’s Q1 2024 precedent table lists roofing contracting deals with investors and a deal-size column, and no EBITDA multiple for any of them. | DAVCAP Advisors, Mar 31, 2024 |
The practical reading: when a buyer or broker quotes a roofing multiple, ask which closed deals it comes from and whether it is measured on SDE, adjusted EBITDA or revenue. A 6x on SDE and a 6x on adjusted EBITDA are different prices for the same company.
How does storm revenue change a roofing multiple?
Storm and insurance revenue lowers a roofing multiple because buyers expect it to fall when the weather calms. Profitability Partners values that revenue at 0.5x to 0.7x of the multiple applied to base revenue, and flags companies with 60% or more storm or insurance revenue as a risk. The table applies that factor to a 7x base, the same example the firm uses.
| Storm or insurance share of revenue | Blended multiple, factor 0.5 | Blended multiple, factor 0.7 |
|---|---|---|
| 0% | 7.0x | 7.0x |
| 20% | 6.3x | 6.6x |
| 40% | 5.6x | 6.2x |
| 60% | 4.9x | 5.7x |
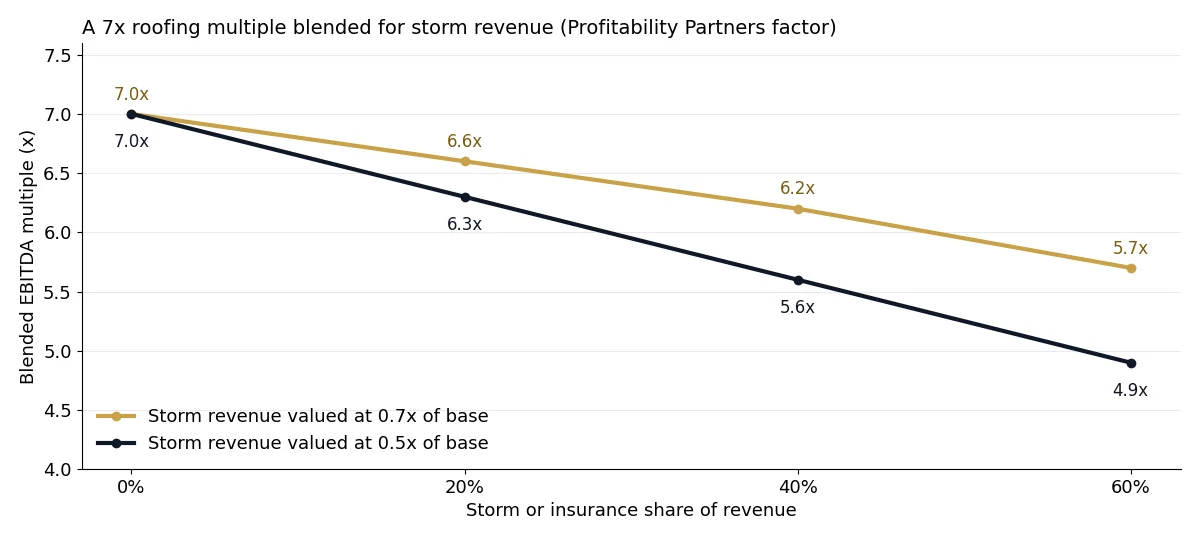
The formula is 7 x (1 − storm share) + 7 x factor x storm share. At 40% storm revenue it gives 5.6x to 6.2x, in line with the “roughly 5.5x to 6x” Profitability Partners reports. Lightning Path Partners puts storm and restoration-dependent roofers at 3x to 3.5x against 4.5x to 5.5x for commercial roofers with contracts.
What moves you up the table is evidence, not argument: three years of revenue split by storm, retail re-roof, repair and commercial maintenance, so the buyer can see the base business. Insurance receivables waiting on carrier supplements also sit in working capital at closing, so collect them before the sale.
What would a $1.5M EBITDA roofing company sell for?
An illustrative roofer with $1.5M of adjusted EBITDA sits in Auxo’s $1.5M to $3.0M band of 4.5x to 6.5x, an enterprise value of $6.75M to $9.75M. If 40% of its revenue came from storm work, the storm factor cuts that to $5.4M to $8.58M. The example is illustrative arithmetic, not a valuation of any real company.
| Step (illustrative) | Low case | High case | Input and source |
|---|---|---|---|
| Adjusted EBITDA | $1.5M | $1.5M | Assumed for the example |
| Base multiple | 4.5x | 6.5x | Auxo $1.5M to $3.0M band |
| Enterprise value before storm adjustment | $6.75M | $9.75M | $1.5M x multiple |
| Multiple with 40% storm revenue | 3.6x (factor 0.5) | 5.72x (factor 0.7) | Base x 0.8 or x 0.88 (1 − 0.4 x 0.5; 1 − 0.4 x 0.3) |
| Enterprise value with 40% storm revenue | $5.4M | $8.58M | $1.5M x adjusted multiple |
| Cash at closing if 20% is rolled into the buyer | $5.4M on the $6.75M case | Not shown | Profitability Partners cites 20% to 30% rollover |
Rollover equity is paid when the platform itself sells, so it is a second payment at an unknown price, not cash today. In the low case, $1.35M of the $6.75M rides on the platform’s next sale; see how rollover equity works in a business sale and how earnouts work.
Who is buying roofing companies in 2026?
Private equity-backed platforms are the main buyers of roofing companies with $3M or more of EBITDA, and individual buyers financed with SBA 7(a) loans dominate below $500K. Roofing Contractor counts 134 contractors acquired by platforms in 2024; Hyde Park Capital counts 53 reported transactions, because it counts only deals that were reported.
| Your adjusted EBITDA | Most likely buyer | Published range | What limits the price |
|---|---|---|---|
| Under $500K | Individual owner-operator, often with an SBA 7(a) loan | 2.5x to 4.0x (Auxo) | 7(a) loans are capped at $5 million (SBA) |
| $500K to $3.0M | Local competitors, search funds, platform add-ons | 3.5x to 5.5x and 4.5x to 6.5x (Auxo) | Owner dependency and storm share |
| $3.0M to $7.5M | New private equity platforms; Bertram Capital states a $3M to $7.5M EBITDA target | 5.5x to 8.0x (Auxo) | Quality of earnings review and management depth |
| Above $7.5M | Established platforms and strategic buyers such as FirstService | 7.0x to 9.0x+ (Auxo) | Number of platforms bidding in your region |
Bertram Capital’s stated range comes from its January 30, 2024 release on Ridgeline Roofing & Restoration. Sponsor-by-sponsor detail, with each platform’s latest dated deal, is in the 2026 roofing PE roll-up tracker, and regional demand is ranked in our roofing roll-up opportunity by region report.
Which roofing multiple should you plan around?
Plan around the published band for your EBITDA size, then adjust for the two items buyers check first: storm share and owner dependency. If your situation matches a row below, the right-hand column is the next step, and every threshold comes from the sources named in the tables above.
| If your situation is | Plan around | Do this before a sale |
|---|---|---|
| If adjusted EBITDA is under $500K and you run the crews | 2.5x to 4.0x on SDE or EBITDA equivalent (Auxo) | Expect a buyer with an SBA 7(a) loan, capped at $5 million; document your own hours so they can be added back. |
| If adjusted EBITDA is $1.5M to $3.0M | 4.5x to 6.5x (Auxo) | Put a non-owner sales lead and production lead in place; Lightning Path Partners takes 0.5x to 1.0x off for owner dependency or customer concentration. |
| If adjusted EBITDA is $3.0M to $7.5M | 5.5x to 8.0x (Auxo) | Commission a sell-side quality of earnings review and approach platforms like Bertram Capital whose stated target is $3M to $7.5M of EBITDA. |
| If storm or insurance work is 60% or more of revenue | Your base multiple x 0.5 to 0.7 on that revenue (Profitability Partners) | Show three years of revenue by source and grow retail re-roof and repair before going to market. |
| If one customer is above 15% to 20% of revenue | The low end of your band | Get the contract in writing for the transition period or reduce the share first (Profitability Partners threshold). |
| If a buyer quotes a multiple with no deal behind it | The band for your size, not the quote | Ask whether it is on SDE, adjusted EBITDA or revenue, and what is paid at closing versus rolled or earned out. |
Valuation detail for owner-run roofers, including the add-backs buyers accept, is in our roofing business valuation guide, and the sale steps are in how to sell a roofing business. Owner dependency is covered in how owner dependency affects valuation.
We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. CT Acquisitions runs confidential sales, recapitalizations and exit planning for founder-owned roofing companies with a 500+ buyer network; book a confidential call to find out which band your company sits in.
How we compiled this
We read 23 primary and published documents in November 2026: buyer press releases, trade reports and an SEC 8-K for seven priced roofing transactions, five advisor pages from four firms that publish roofing multiples, three market reports (KPMG, Hyde Park Capital, DAVCAP Advisors) and trade coverage from Roofing Contractor and NRCA. Implied multiples are our arithmetic from the stated price and profit or sales. We excluded forum posts and any range we could not trace to a named publisher; the July 2026 version of this page was rewritten because its PitchBook, GF Data and BizBuySell figures could not be verified.
Frequently asked questions
What EBITDA multiple do roofing companies sell for in 2026?
Published 2026 ranges put roofing companies at about 2.5x to 4.0x adjusted EBITDA below $500K, 5.5x to 8.0x at $3.0M to $7.5M and 7.0x to 9.0x+ above $7.5M (Auxo Capital Advisors, June 2026). No public dataset of closed roofing contractor deals backs these ranges, so treat them as one advisor’s estimate.
Why are private equity firms buying roofing companies?
Private equity buys roofing companies because the trade is fragmented and replacement work recurs. KPMG puts the US roofing contracting market above $50 billion with the top three firms holding about 6%, and Roofing Contractor counts 134 contractors bought by platforms in 2024, up from 106 in 2023.
What roofing companies are owned by private equity?
Tecta America (Altas Partners), Ridgeline Roofing (Bertram Capital) and Erie Home (Gridiron, now combined with Leaf Home) are private equity owned, while Roofing Corp of America has been controlled by FirstService, a public company, since December 2023. Our roofing PE roll-up tracker lists 17 platforms with dated releases.
Does storm restoration revenue lower a roofing company’s multiple?
Yes. Profitability Partners values storm and insurance revenue at 0.5x to 0.7x of the base multiple, so a 7x roofer with 40% storm revenue prices near 5.6x to 6.2x. Three years of revenue split by source, showing a steady retail and repair base, is the evidence buyers use to narrow that discount.
What is the highest multiple paid in roofing M&A?
Among priced roofing deals since 2021, LafargeHolcim’s USD 3.4 billion purchase of Firestone Building Products is the highest we found at about 12.6x 2020 estimated EBITDA of USD 270 million. That is a manufacturer; the contractor prices on record, Roofing Corp of America and Tecta America, are stated against revenue.
Sources
- Auxo Capital Advisors, Roofing Company Valuation Multiples, June 4, 2026 (accessed Nov 12, 2026)
- Profitability Partners, Roofing Company Valuation, updated Nov 8, 2026; How to Sell Your Roofing Business, updated Oct 19, 2026 (accessed Nov 12, 2026)
- Lightning Path Partners, Roofing EBITDA Multiples, 2026 (accessed Nov 12, 2026)
- Peak Business Valuation, Roofing Company Multiples, undated (accessed Nov 12, 2026)
- Bridgestone Americas, LafargeHolcim to acquire Firestone Building Products, Jan 7, 2021
- Holcim, Holcim to acquire Malarkey Roofing Products, Dec 23, 2021
- Roofing Contractor, Holcim completes $1.29 billion Duro-Last roofing acquisition, Apr 3, 2023
- NRCA Roofing News, FirstService Corporation acquires Roofing Corp of America, Dec 20, 2023
- The Home Depot, agreement to acquire SRS Distribution, Mar 28, 2024
- Roofing Contractor, Is Tecta America for Sale?, Nov 27, 2024
- QXO, QXO to Acquire Beacon Roofing Supply for $11 Billion, Mar 20, 2025; QXO Completes Acquisition, Apr 29, 2025
- Beacon Roofing Supply, Q4 2024 earnings release (SEC Form 8-K), Feb 27, 2025
- Roofing Contractor, Roofing’s Big Deal, Feb 20, 2025
- Hyde Park Capital, Roofing Services Market Insights, Jul 8, 2025
- KPMG Corporate Finance, Roofing Contracting: M&A Market Update 2025 (accessed Nov 12, 2026)
- DAVCAP Advisors, Roofing Q1 2024 Review, Mar 31, 2024
- PR Newswire, Bertram Capital partners with Ridgeline Roofing & Restoration, Jan 30, 2024; Leaf Home acquires Erie Home, Sep 8, 2025
- Roofing Contractor, Soundcore Capital Partners announces sale of Roofing Corporation of America, Dec 18, 2023
- Tecta America, Tecta America acquires Skyline Roofing, Oct 14, 2025
- U.S. Small Business Administration, 7(a) loans (accessed Nov 12, 2026)
Related research: the 2026 home services M&A multiples report compares roofing with HVAC, plumbing and electrical, and the HVAC M&A multiples report is the closest sibling.
Related research: for the 2026 Home Services M&A Multiples Report, the cluster pillar comparing home services sub-verticals, see the linked report.
Related research: for the 2026 HVAC M&A Multiples Report, sibling home services spoke, see the linked report.
Related research: for the 2026 Landscaping and Lawn Care M&A Multiples Report, sibling home services spoke covering counter-seasonal snow-mix premium, see the linked report.
