
Accounting Firm Valuation in 2026: CPA Firm Multiples, 0.8x to 1.25x Revenue, and What PE Platforms Pay
Accounting firm valuation: a CPA firm sold to another CPA usually prices at 0.8x to 1.25x annual fees, paid over years and cut if clients leave; PE-backed platforms instead price normalized EBITDA after resetting partner pay.
Key takeaways
- Small CPA firms have sold for up to 1.25x billings with 0% to 20% down and payouts of three to 10 years tied to collections (Journal of Accountancy, 2013).
- Broker conventions in 2026 run from 80% to 120% of gross (Accounting Practice Sales) to 1.1x to 1.3x for well-structured firms (Poe Group Advisors).
- Internal buyouts price lower: 43% of firms in the 2012 PCPS Succession Survey used 1x revenue and 35% used three times compensation (Journal of Accountancy, 2014).
- As of Q3 2025, 11 of the 30 largest U.S. accounting firms had taken private equity investment (KPMG Corporate Finance).
- CBIZ agreed to pay about $2.3 billion for Marcum’s non-attest business, about 1.9x Marcum’s $1.2 billion of revenue (CBIZ SEC filing, July 31, 2024).
- State rules keep audit work CPA-owned (Georgia Rule 20-7-.02 requires a simple majority of CPA ownership), so PE buys only the non-attest firm.
Thinking about selling your accounting firm?
Skip the formulas. A 15-minute confidential call gives you a real valuation range and tells you which buyers would compete for your business. No cost, no obligation.
How much is an accounting firm worth in 2026?
An accounting firm is worth roughly one times its annual fees when another CPA firm buys it, with published conventions running from 80% to 125% of fees and most of the price paid over four to six years. Larger deals with disclosed terms priced higher: CBIZ’s Marcum purchase implies about 1.9x revenue, and Citrin Cooperman’s 2021 recapitalization about 1.43x.
| Source | What it measures | Multiple | Payment terms | Date |
|---|---|---|---|---|
| Journal of Accountancy | External sales of small CPA firms | Up to 1.25x billings; some remote firms below 1x | 0% to 20% down (typical 10%); three to 10 year payout on collections | Nov 2013 |
| Accounting Practice Sales | Broker convention for practice sales | 80% to 120% of gross | Example: 20% down, then 20% a year for four years | Accessed Oct 2026 |
| Poe Group Advisors | Well-structured CPA firm sales | 1.1x to 1.3x gross; 1.4x or more for exceptional firms | All cash at closing without a retention guarantee is possible | Mar 2026 |
| 2012 PCPS Succession Survey | Internal retirement buyouts | 43% use 1x revenue; 35% use 3x compensation | Payouts stretching to 10 years or more | Dec 2014 |
| CBIZ Form DEFA14A | Marcum non-attest business (public buyer) | About $2.3 billion on about $1.2 billion revenue: about 1.9x | About half cash, half CBIZ stock | Jul 2024 |
| Private Equity Wire, citing the Financial Times | Citrin Cooperman platform | 11x EBITDA (2021), about 15x (2025); $500 million on $350 million revenue: about 1.43x | Not disclosed | Jan 2025 |
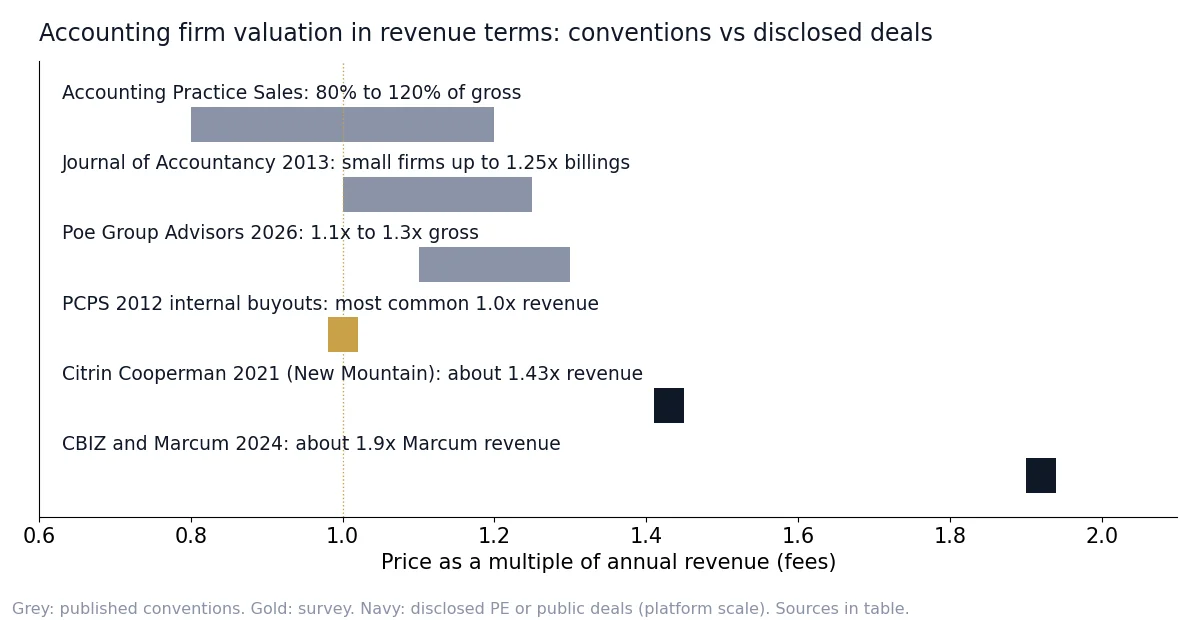
Read the last two rows as platform prices, not small-firm prices. Marcum was the 13th-largest U.S. accounting firm with more than 3,500 professionals, and Citrin Cooperman reached $850 million of revenue in 2024. A single-office practice with $2 million of fees is priced against the first three rows, because its likely buyer is another CPA firm.
How does the free accounting firm valuation calculator work?
The CT Acquisitions calculator for CPA and accounting firms takes your annual fees, earnings and practice details and returns a starting-point range built on the conventions in the table above, from 80% to 125% of fees. It is a screening estimate, not a formal appraisal, a Quality of Earnings review or an offer from a buyer, and it is also available as a standalone CPA firm valuation calculator.
How does the one-times-fees convention work in a CPA-to-CPA sale?
In a CPA-to-CPA sale the headline price is a multiple of annual fees, usually near 1.0x, but most of it arrives later and only for clients who stay. The Journal of Accountancy found down payments of 0% to 20% in more than 90% of the deals its authors handled, with payouts of three to 10 years and the price adjusted to collections.
- Measure the fee base. Use trailing 12 months of fees from clients who will transfer. The seller usually keeps cash and accounts receivable (Journal of Accountancy, 2013; Accounting Practice Sales).
- Set the multiple. 0.8x to 1.25x of fees per the table above. Firms in remote areas can struggle to reach 1x billings, and larger firms get smaller multiples and longer payouts (Journal of Accountancy, 2013).
- Agree the down payment. 0% to 20% of the price, typically 10% (Journal of Accountancy, 2013).
- Define the retention period. The price is recalculated on fees collected from transferred clients; one-year retention periods are rare and longer ones are more common (Journal of Accountancy, 2013).
- Set the payout. Four to six years for smaller firms, usually without interest (Journal of Accountancy, 2013). Poe Group Advisors shows an offer paying 20% of collections over four years.
- Write the clawback rules. Name which losses reduce the price: clients who die or sell their business, clients the buyer drops, and clients who leave after a fee increase the buyer imposes.
Terms and multiple trade against each other. The 2013 Journal of Accountancy authors found that less cash up front, longer payouts and longer retention periods push the multiple higher. Poe Group Advisors notes the other end of the trade: a seller can take all cash at closing with no client retention guarantee. The guide to selling an accounting firm covers the sale process step by step.
How much of a 1.0x price does the seller collect?
Less than the headline. On $1.5 million of fees sold at 1.0x with 10% down and the balance over five years, the seller’s payments are worth about $1,228,000 today at an 8% discount rate if every client stays, and about $988,000 if 20% of fees leave. These are CT Acquisitions estimates (illustrative) built on Journal of Accountancy deal norms.
| Scenario | Price after retention | Down payment | Annual payment, years 1 to 5 | Present value at 8% | As a multiple of original fees |
|---|---|---|---|---|---|
| 100% of fees retained | $1,500,000 | $150,000 | $270,000 | $1,228,000 | 0.82x |
| 90% retained | $1,350,000 | $150,000 | $240,000 | $1,108,000 | 0.74x |
| 80% retained | $1,200,000 | $150,000 | $210,000 | $988,000 | 0.66x |
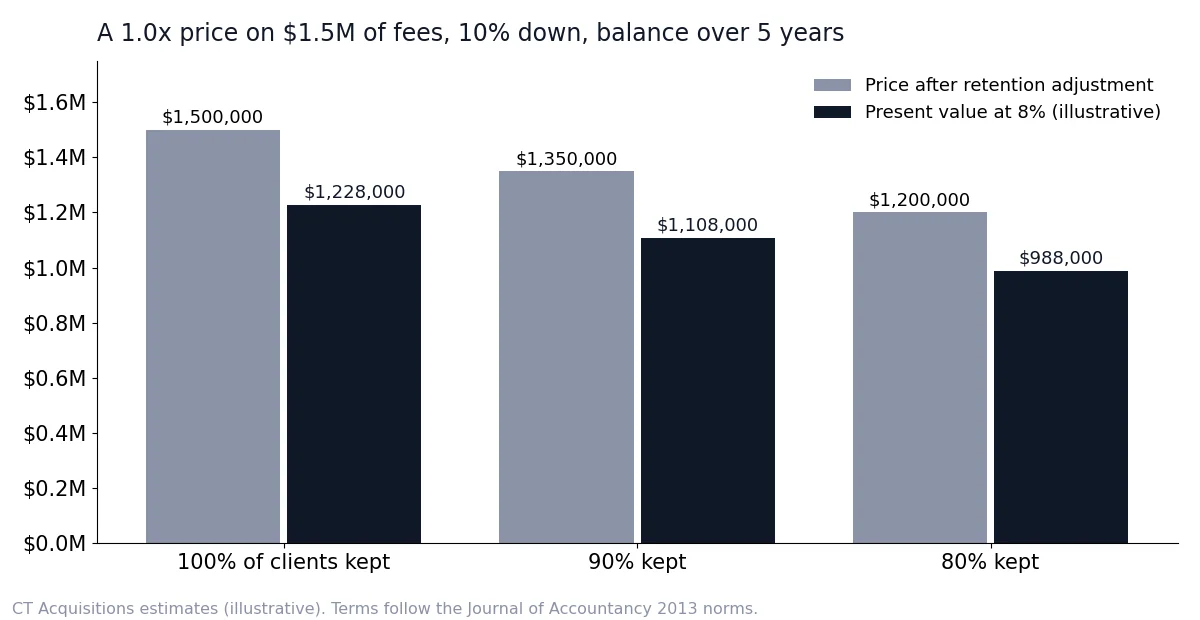
Two levers move what you collect more than the headline multiple: the share of fees that stays and how fast the money arrives. The protections to ask for in the letter of intent are a retention period that covers at least one full tax season, personal introductions to your largest clients by fees, and a clause that excludes clients the buyer drops or reprices from the clawback. The guide to earnouts shows how contingent payments are drafted and disputed.
How is an internal partner buyout priced?
Internal buyouts usually price lower than outside sales. In the 2012 PCPS Succession Survey reported by the Journal of Accountancy, 43% of firms with retirement agreements used 1x revenue and 35% used three times the retiring owner’s compensation. Payouts are increasingly stretched to 10 years or more and are funded from the remaining partners’ cash flow.
| Buyout method | Share of firms (2012 PCPS) | How the multiple was set | Source |
|---|---|---|---|
| Ownership share times firm value | 37% | Firm valued on revenue: 43% at 1x, 22% at 0.8x to 1x, 24% below 0.8x, 8% above 1x | Journal of Accountancy, Dec 2014 |
| Multiple of compensation | 22% | 35% at 3x, 17% at 2.5x, 35% below 2.5x, 12% above 3x | Journal of Accountancy, Dec 2014 |
| Book of business | 16% | Multiple applied to the retiring partner’s own managed clients | Journal of Accountancy, Dec 2014 |
| Other or hybrid | 25% | Fixed values and blends of the methods above | Journal of Accountancy, Dec 2014 |
The methods converge more than they look. With owner pay at the classic 33% of revenue, three times compensation equals one times revenue (Journal of Accountancy, 2014). The 2013 article sets the funding test: the retiring partner’s pay minus the cost of replacing that partner’s work must cover the payments and still leave the remaining partners some upside. Its example pays a partner with $100,000 of average pay $300,000 over 10 years, plus capital. For valuing a partner’s share before a buyout, see business valuation before a partnership buyout.
What changed when private equity entered accounting?
Private equity created a third buyer that pays for profit rather than fees. TowerBrook’s August 2021 investment in EisnerAmper opened the wave; by Q3 2025, 11 of the 30 largest U.S. accounting firms had taken PE money, per KPMG Corporate Finance, and the Journal of Accountancy counts more than 53 PE transactions from 2020 to mid-2025, 24 of them in 2024.
| Date | Firm | Investor or buyer | What the record shows | Source |
|---|---|---|---|---|
| Aug 2021 | EisnerAmper | TowerBrook Capital Partners | Attest stayed in EisnerAmper LLP; 27 add-on acquisitions by March 2026, when Carlyle AlpInvest led a continuation vehicle | TowerBrook release, Mar 25, 2026 |
| Late 2021 | Citrin Cooperman | New Mountain Capital | About $500 million enterprise value at 11x EBITDA, as reported | Private Equity Wire |
| Jun 30, 2022 | Cherry Bekaert | Parthenon Capital | Attest in Cherry Bekaert LLP; advisory in Cherry Bekaert Advisory LLC; terms not disclosed | Cherry Bekaert release |
| Feb 2024 | Baker Tilly US | Hellman & Friedman, Valeas Capital Partners | Top 10 U.S. firm | Journal of Accountancy, Mar 2024 |
| Mar 2024 | Grant Thornton | New Mountain Capital | Second PE deal in a top 10 firm in 2024 | Journal of Accountancy, Mar 2024 |
| Jul 11, 2024 | Aprio | Charlesbank Capital Partners | Terms not disclosed | Inside Public Accounting |
| Jul 31, 2024 | Marcum | CBIZ (NYSE: CBZ) | Non-attest business for about $2.3 billion; attest to Mayer Hoffman McCann P.C. | CBIZ SEC filing |
| Nov 18, 2024 | PKF O’Connor Davies | Investcorp, PSP Investments | Terms not disclosed | PKF O’Connor Davies release |
| Jan 7, 2025 | Citrin Cooperman | Blackstone (buying New Mountain’s stake) | About 15x EBITDA, as reported | Blackstone release |
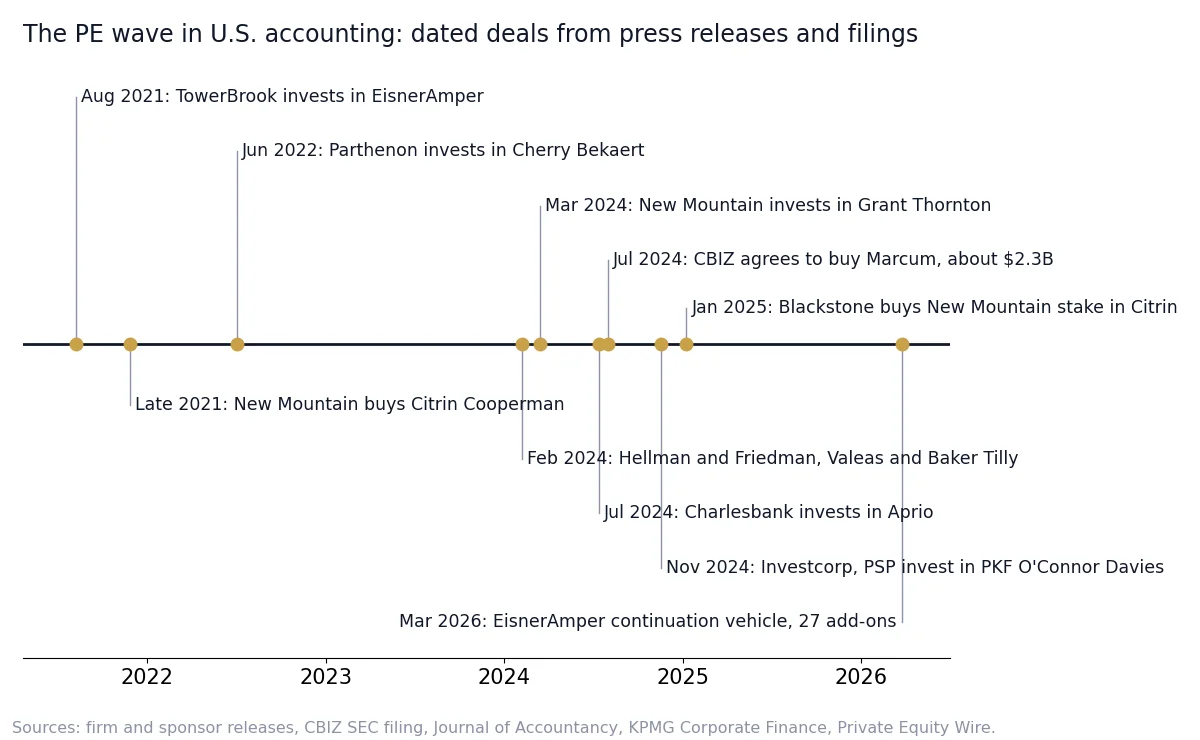
The wave is concentrated at the top. KPMG Corporate Finance estimates 46,000 to 52,200 CPA firms in the U.S. and finds PE money in only 5% of the top 2,000, so most owners still sell to another CPA firm or to their own partners. PE platforms reach smaller firms through tuck-in acquisitions; the map of who buys CPA firms in 2026 lists the active acquirers.
How do PE platforms price a CPA firm differently?
A PE platform prices normalized EBITDA, which exists only after partner pay is reset to a market salary. Allan Koltin told the Journal of Accountancy in 2021 that partners give back some profitability and PE puts a multiple on it; the largest payment comes at closing, a second about three years later, and the last when the sponsor sells in years five to seven.
Koltin also described the ownership terms: PE typically takes more than 50% but probably not more than 75% of the firm and holds it for four to seven years, and average equity partner pay of $700,000 or more makes a deal easier. The partners’ retained stake is rollover equity, which pays only when the platform is sold.
Why can PE buy only the non-attest part of the firm?
State boards require CPAs to own most of a licensed firm. Georgia Rule 20-7-.02 requires a simple majority of financial interest and voting rights held by CPAs and bars non-CPA owners from being solely or predominately passive investors. So PE deals split the firm: audit and review work stays in a CPA-owned firm, and the investor buys the tax and advisory entity, as Cherry Bekaert did in 2022.
CBIZ applied the same rule to Marcum: it bought the non-attest business, and Marcum’s attest practice went to Mayer Hoffman McCann P.C. If audit and review work is a large share of your fees, ask the buyer in writing how the attest firm’s partners are paid and whether attest fees count toward your price before you sign a letter of intent.
What EBITDA multiple matches the revenue convention?
Divide the revenue multiple by the EBITDA margin left after the pay reset. At a 15% margin, a PE buyer must pay 6.7x EBITDA to match 1.0x revenue and 8.3x to match 1.25x; at a 25% margin, 4.0x and 5.0x. These break-even figures are CT Acquisitions estimates (illustrative), pure arithmetic with no market quote behind them.
| EBITDA margin after pay reset | Multiple to match 1.0x revenue | Multiple to match 1.25x revenue |
|---|---|---|
| 10% | 10.0x | 12.5x |
| 15% | 6.7x | 8.3x |
| 20% | 5.0x | 6.25x |
| 25% | 4.0x | 5.0x |
| 30% | 3.3x | 4.2x |
| 35% | 2.9x | 3.6x |
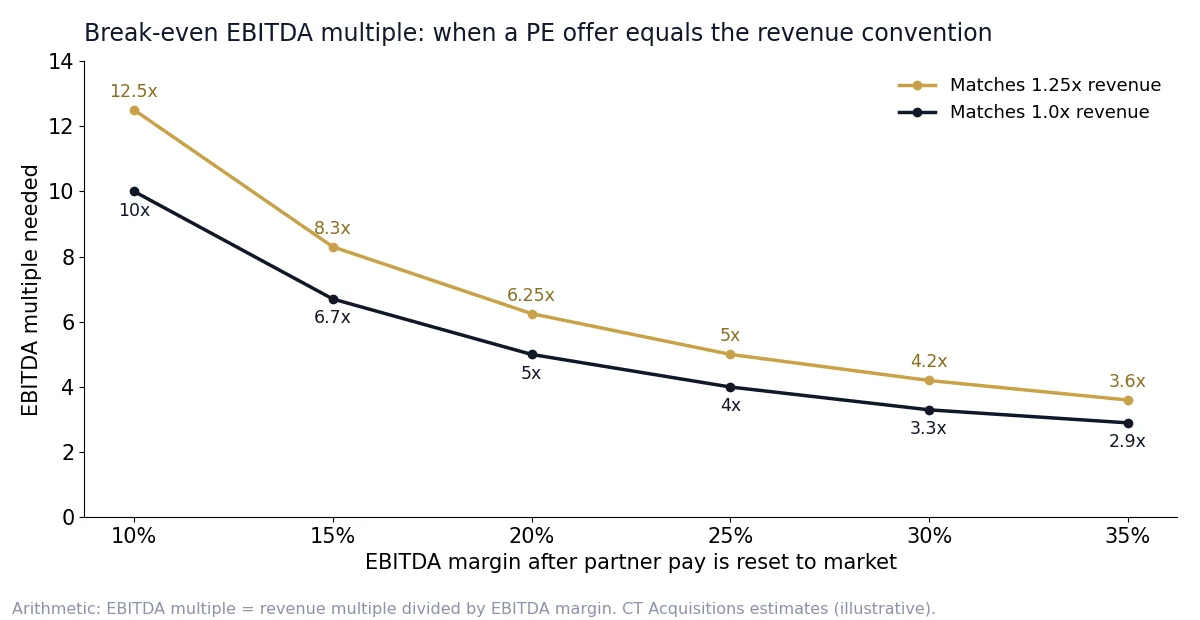
Citrin Cooperman shows the arithmetic at platform scale. About $500 million of enterprise value at 11x EBITDA on $350 million of revenue implies EBITDA near $45.5 million, a margin of about 13%, and a revenue multiple of about 1.43x (Private Equity Wire, citing the Financial Times). A smaller firm at the same 13% margin would need about 7.7x EBITDA just to match 1.0x revenue.
What would the same firm fetch from three different buyers?
A $3 million firm with three partners earning $400,000 each gets very different prices and cash timing from each buyer. In this CT Acquisitions illustrative model, an outside CPA firm pays $3,000,000 with $300,000 at closing, while a PE platform at an assumed 7x pays $3,150,000 with $2,205,000 at closing and takes $450,000 a year of partner pay.
| Line | Outside CPA firm | Internal buyout (one retiring partner) | PE platform |
|---|---|---|---|
| Pricing basis | 1.0x fees | 3x the retiring partner’s pay | Assumed 7x EBITDA after pay reset |
| Headline value | $3,000,000 (whole firm) | $1,200,000 (one third) | $3,150,000 (non-attest firm) |
| In revenue terms | 1.0x | 1.2x (3x total pay of $3,600,000) | 1.05x |
| Cash at closing | $300,000 (10% down) | Capital account only | $2,205,000 (assumed 70%) |
| Paid later or at risk | $540,000 a year for 5 years, on collections | $120,000 a year for 10 years | $945,000 rollover, paid on sponsor exit |
| Present value at 8% | $2,456,000 at full retention | $805,000 | Depends on the exit value |
| Partner pay after closing | Seller exits | Remaining partners keep $400,000 each | Reset to an assumed $250,000 each: $450,000 a year less in total |
The PE column is the one owners misread most often. The $3,150,000 is 7 times the $450,000 of pay the partners give up each year, so over five years they forgo $2,250,000 of compensation to receive it. That trade suits partners who want cash now and will keep working through the four to seven year hold Koltin describes; a sole owner who wants to stop working is usually better served by the outside sale.
What raises or lowers an accounting firm’s multiple?
Size, location, deal terms and partner pay move the multiple most in the sources reviewed. The Journal of Accountancy found larger firms get smaller multiples with longer payouts, remote firms can struggle to reach 1x billings, and smaller down payments with longer retention periods support higher multiples; Koltin put the easier PE threshold at $700,000 of average equity partner pay.
| Driver | Effect on price | Source |
|---|---|---|
| Firm size (sale to a CPA firm) | Larger firms get smaller multiples and longer payouts | Journal of Accountancy, 2013 |
| Location | Firms in remote areas can struggle to reach 1x billings | Journal of Accountancy, 2013 |
| Cash at closing | More cash up front pulls the multiple down | Journal of Accountancy, 2013 |
| Retention period | Longer retention periods support a higher multiple | Journal of Accountancy, 2013 |
| Buyer overhead | A low-overhead buyer can pay more; required staff retention lowers offers | Journal of Accountancy, 2013 |
| Average equity partner pay | $700,000 or more makes a PE deal easier | Journal of Accountancy, 2021 (Koltin) |
| Attest share | Attest stays CPA-owned and sits outside a PE purchase | Georgia Rule 20-7-.02; CBIZ SEC filing |
Practice mix changes which page applies. Tax-only practices are priced on return counts and fee per return; see tax preparation business valuation. Bookkeeping practices with monthly billing are covered in the guide to selling a bookkeeping business, and CPAs who perform valuations for clients should read CPA business valuation.
Which route fits your accounting firm?
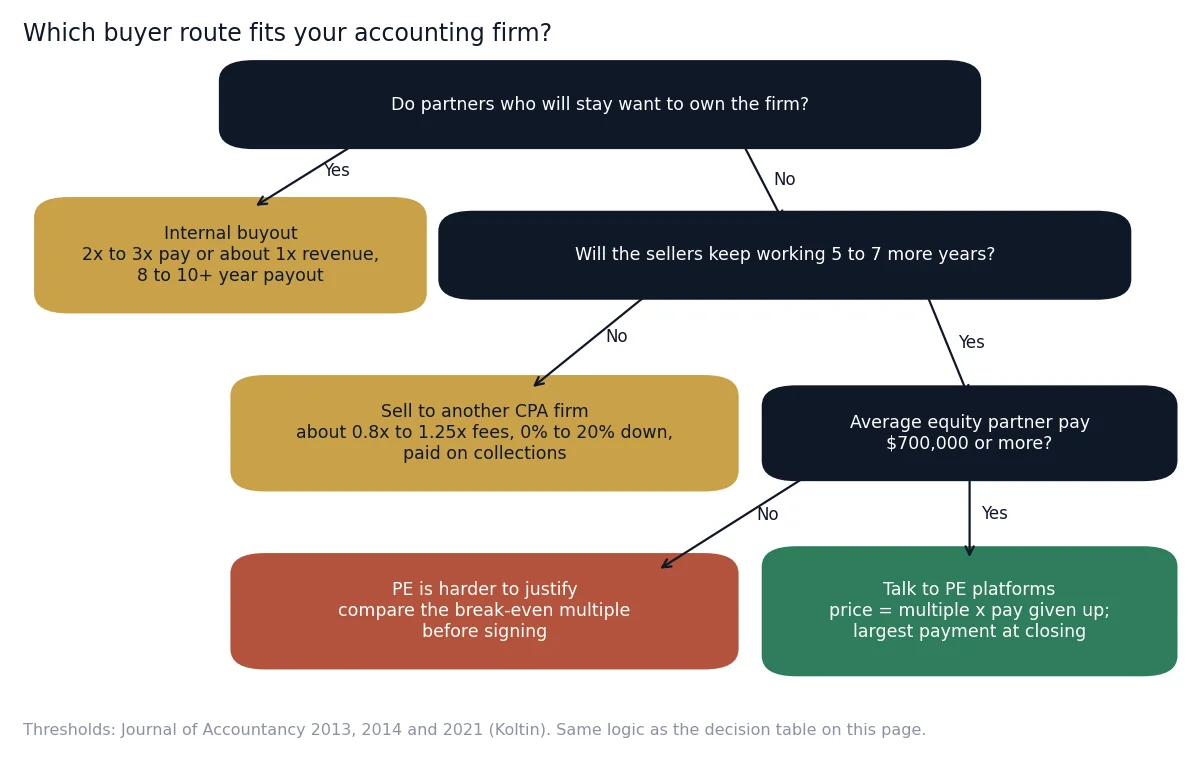
Pick the buyer before you pick the number. The decision table turns the thresholds in the Journal of Accountancy articles and the CBIZ and Citrin Cooperman disclosures into rules: who stays, how long you will keep working, partner pay against Koltin’s $700,000 marker, and the EBITDA multiple an offer must clear to beat 1.0x revenue.
| If your situation is | Do this | Why |
|---|---|---|
| Sole owner or retiring partners, and no partner will stay | Sell to another CPA firm at about 0.8x to 1.25x fees with a retention payout | Journal of Accountancy, 2013; Poe Group Advisors, 2026 |
| Younger partners want to keep the firm | Price an internal buyout at about 1x revenue or 2.5x to 3x pay, paid over 10 years or more, after the cash-flow test | 2012 PCPS Succession Survey |
| Average equity partner pay of $700,000 or more and partners will work five to seven more years | Run a PE process alongside a CPA-firm process | Journal of Accountancy, 2021 (Koltin) |
| A PE offer whose multiple times post-reset margin is below 1.0x | Compare cash at closing and present value, not the headline | Break-even table above |
| Audit and review are a large share of fees | Get the attest firm’s terms in writing before the letter of intent | Georgia Rule 20-7-.02; CBIZ and Marcum |
| You hold C corporation stock and hope to use QSBS | Do not count on Section 1202 | 26 U.S.C. 1202(e)(3)(A) excludes accounting |
Owners with 12 to 24 months before a sale can work through the accounting firm exit prep playbook first. CT Acquisitions is an M&A advisory firm for founder-owned businesses, working sell side, buy side and exit planning across a network of 500+ buyers. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing.
Want to know what your accounting firm is worth?
Benchmarks give you a range. A 15-minute confidential call gives you a real number, based on what active buyers are paying right now and which ones would compete for your business. No cost, no obligation.
How we compiled this
We compiled this page in October 2026 from 17 documents: five Journal of Accountancy articles (2013, 2014, 2021, 2024 and 2025), CBIZ’s SEC filing on Marcum, four firm or sponsor press releases, one state board rule, the Internal Revenue Code, KPMG Corporate Finance’s industry update, two advisor-published practice-sale conventions and two trade reports. We did not survey buyers or use client deal data. We excluded forum threads, AI-generated estimates and multiples that no named document supports; worked examples are CT Acquisitions estimates (illustrative).
Frequently asked questions
How do you value a CPA firm for sale?
Start with the trailing 12 months of fees from clients who will transfer, apply the market convention of about 0.8x to 1.25x, then adjust for terms: down payment, retention period and payout years. The Journal of Accountancy found 0% to 20% down in more than 90% of the deals its authors handled. Firms with PE-level profit can also get an EBITDA price after partner pay is reset.
How much is my CPA firm worth?
Most small and midsize CPA firms are worth about one times annual fees to another CPA firm: Accounting Practice Sales cites 80% to 120% of gross and Poe Group Advisors 1.1x to 1.3x for well-structured firms in 2026. What you collect depends on client retention; a 1.0x price paid over five years is worth about 0.82x today at an 8% discount rate (illustrative).
What multiple do private equity firms pay for accounting firms?
Few PE prices are public. The Financial Times, as reported by Private Equity Wire, put New Mountain Capital at about 11x EBITDA for Citrin Cooperman in 2021 and Blackstone at about 15x in 2025. Those are platform prices for a firm with $850 million of 2024 revenue. Tuck-in prices for small firms are not disclosed, so test any offer against the break-even multiple.
What does a 10x EBITDA multiple mean for an accounting firm?
It means a price of ten times the firm’s annual EBITDA, measured after partner pay is reset to a market salary. At a 10% EBITDA margin, 10x equals exactly 1.0x revenue, the same as the CPA-to-CPA convention; at a 20% margin it equals 2.0x revenue. The margin after the pay reset decides whether a big multiple is a good price.
How do buyers adjust the price for client retention?
Most CPA-to-CPA deals pay the price from collections, so it is recalculated on the fees the buyer collects from your clients during a retention period, which the Journal of Accountancy says is rarely as short as one year. If 20% of fees leave, a $1.5 million price at 1.0x falls to $1.2 million. Negotiate in the letter of intent which client losses count against you.
Can a CPA perform a business valuation?
Yes. Many CPAs value businesses, and the AICPA’s Accredited in Business Valuation (ABV) credential is the CPA-specific designation. A sale of your own firm is priced differently: buyers apply market conventions and deal terms, so treat a formal valuation as one input and compare it with the 0.8x to 1.25x fee convention and the cash you would receive at closing.
Does QSBS (Section 1202) apply when I sell my accounting firm?
Generally no. Section 1202(e)(3)(A) of the Internal Revenue Code excludes any trade or business performing services in the field of accounting from qualified small business stock, so stock in a C corporation CPA firm does not qualify for the exclusion of up to $10 million or $15 million of gain. Ask your tax adviser how asset or stock structure changes your capital gain instead.
Is an accounting firm worth 3 times profit?
It can be, if profit means the owner’s full earnings. Three times owner compensation was the most common internal buyout multiple in the 2012 PCPS Succession Survey, used by 35% of firms, and at owner pay of 33% of revenue it equals one times revenue, per the Journal of Accountancy. Measured after a market salary for the owner, profit is smaller and the multiple is higher.
Sources
- Journal of Accountancy, How to value a CPA firm for sale (Sinkin and Putney), November 1, 2013. Accessed October 2026.
- Journal of Accountancy, How to price an owner’s interest in a CPA firm (2012 PCPS Succession Survey), December 1, 2014. Accessed October 2026.
- Journal of Accountancy, Private equity’s push into accounting (Allan Koltin interview), October 6, 2021. Accessed October 2026.
- Journal of Accountancy, Grant Thornton deal continues the private-equity investment trend, March 18, 2024. Accessed October 2026.
- Journal of Accountancy, What faculty should know about private equity in accounting, September 8, 2025. Accessed October 2026.
- CBIZ, Inc. Form DEFA14A (Marcum transaction announcement), July 31, 2024. Accessed October 2026.
- Blackstone press release on Citrin Cooperman, January 7, 2025. Accessed October 2026.
- Cherry Bekaert press release on Parthenon Capital, June 30, 2022. Accessed October 2026.
- PKF O’Connor Davies press release on Investcorp and PSP Investments, November 18, 2024. Accessed October 2026.
- TowerBrook press release on the EisnerAmper continuation vehicle, March 25, 2026. Accessed October 2026.
- Georgia Rule 20-7-.02, Firm Ownership (Cornell Legal Information Institute). Accessed October 2026.
- 26 U.S. Code 1202, Partial exclusion for gain from certain small business stock (Cornell Legal Information Institute). Accessed October 2026.
- KPMG Corporate Finance, Professional Services Industry Update, Winter 2025. Accessed October 2026.
- Accounting Practice Sales, One Times Gross: Is that the law?. Accessed October 2026.
- Poe Group Advisors, What is the Value of an Accounting Practice?, updated March 9, 2026. Accessed October 2026.
- Inside Public Accounting, Aprio announces investment from Charlesbank Capital Partners, July 12, 2024. Accessed October 2026.
- Private Equity Wire, Blackstone leads deal for majority stake in Citrin Cooperman (citing the Financial Times), January 9, 2025. Accessed October 2026.

About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm working both sides of the table, headquartered in Sheridan, Wyoming. We work directly with 500+ buyers, search funders, family offices, lower middle-market PE, and strategic consolidators, including direct mandates with the largest consolidators that other intermediaries cannot access. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing. Connect on LinkedIn · Get in touch
Related Guide: Law Firm Valuation (2026), Multiples, partner retention, and the LMM legal services buyer pool.
Related Guide: Consulting Business Valuation (2026), Boutique consulting firm multiples and the recurring-services premium.
Related Guide: Buyer Archetypes: PE, Strategic, Search Fund, Family Office, How each buyer underwrites differently and what they pay for.
Related Guide: 2026 LMM Buyer Demand Report, Aggregated buy-box data from 76 active U.S. lower middle market buyers.
Related Guide: Business Valuation Calculator (2026), Quick starting-point valuation range based on SDE/EBITDA and industry.
Business valuation experts: who they are and when to hire one
Business valuation experts hold one of three credentials: ABV (AICPA, for CPAs), CVA (NACVA, standalone), or ASA (American Society of Appraisers, most rigorous). For dispute or tax matters, ASA-credentialed experts are the standard. Investment-banker valuations are market-driven rather than credential-driven, and are typically preferred when the purpose is a live sale.
Want a Specific Read on Your Business?
15 minutes, confidential, no contract, no cost. You leave with a read on your local buyer market and a likely valuation range.
The next practical step for owners inside this range is the pre-sale runway checklist, which shows what to fix before going to market.
Owners in this vertical planning a 12- to 24-month runway can start with accounting firm exit prep playbook.
Related M&A guide
Sector deep-dive with named transactions, mapped buyer landscape, and operator-level diligence:
