How to Sell a Fire Protection Business in 2026: Real Multiples, PE Buyer Behavior, and the Recurring-Inspection Premium
To sell a fire protection business, prove the inspection contract book first: buyers pay for code-mandated NFPA 25 and NFPA 72 service work, and in Texas a total ownership change voids the sprinkler registration (28 TAC §34.710).

By Christoph Totter, Founder of CT Acquisitions · Last reviewed: October 2026
Thinking about selling your business?
A 15-minute confidential call gives you a real valuation range and the buyers most likely to compete for your business. No cost, no obligation.
Key takeaways
- Texas treats a total ownership change as the end of the seller’s sprinkler registration: the buyer files a new application, ideally 14 days before the change, because a certificate is “neither temporarily nor permanently transferable” (28 TAC §34.710).
- California gives a contractor 90 days to replace a departing qualifier before the license is automatically suspended (Business and Professions Code §7068.2), so the qualifier’s exit date belongs in the purchase agreement.
- A Florida water-based inspector permit is valid only while the holder works for the certificateholder named on it (Fla. Stat. §633.318(8)), so a new certificateholder re-permits every inspector.
- The recurring work is written into code: NFPA 72 requires an annual test of the entire fire alarm system and NFPA 10 an annual extinguisher maintenance, per the Minnesota Department of Health guides revised June 2024.
- Across all industries, Q4 2025 average multiples were 4.1x EBITDA for $2M to $5M deals and 5.5x for $5M to $50M deals (IBBA and M&A Source Market Pulse).
- Pye-Barker Fire & Safety reported 57 fire alarm, sprinkler, suppression and security acquisitions in 2025 and 9,000 team members across 47 states (company release, March 17, 2026).
What is a fire protection business worth when you sell it?
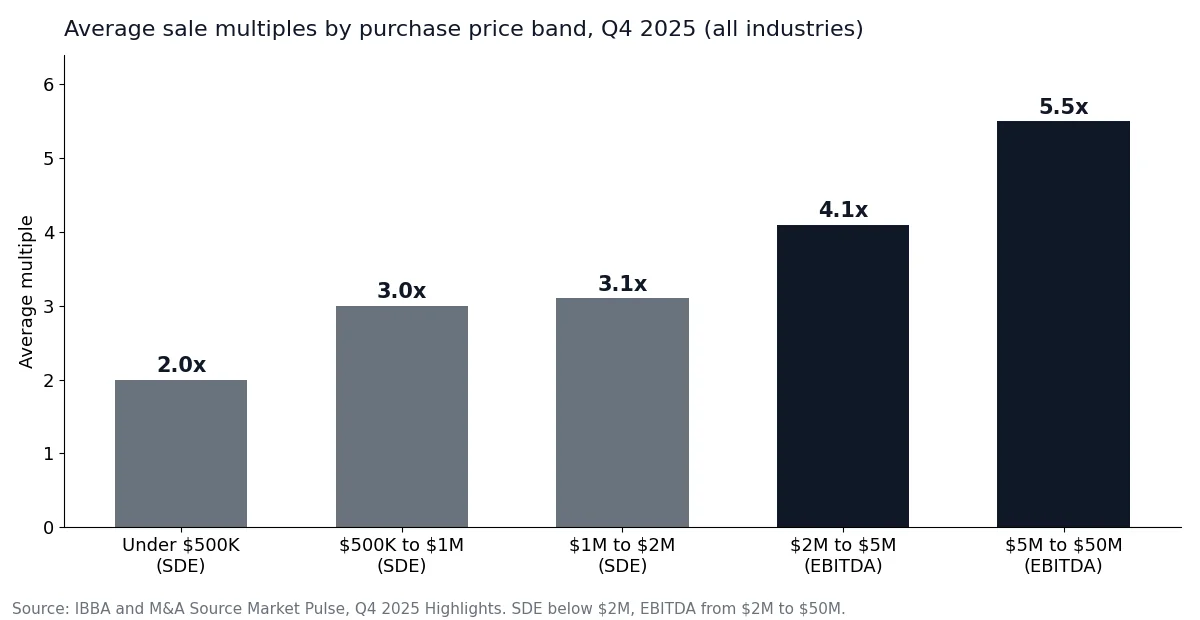
A fire protection business sells on a multiple of earnings that rises with deal size and with the share of revenue under recurring inspection contracts. Across all industries, the IBBA and M&A Source Market Pulse put Q4 2025 averages at 2.0x to 3.1x seller’s discretionary earnings (SDE) below $2M of price, and 4.1x to 5.5x EBITDA from $2M to $50M. Fire protection buyers then adjust for the inspection book.
| Purchase price band | Earnings basis | Average multiple, Q4 2025 | Source |
|---|---|---|---|
| Under $500K | SDE | 2.0x | IBBA and M&A Source Market Pulse Q4 2025 (all industries) |
| $500K to $1M | SDE | 3.0x | Same survey |
| $1M to $2M | SDE | 3.1x | Same survey |
| $2M to $5M | EBITDA | 4.1x | Same survey |
| $5M to $50M | EBITDA | 5.5x | Same survey |
Those are averages across every industry the survey covers. CT Acquisitions works with the fire protection ranges below; they are our advisory estimate, not a published survey, and a buyer’s offer turns on the specific contract book.
| Fire protection business type | CT working range | What moves it to the top of the range | Basis |
|---|---|---|---|
| Owner-operated, project-heavy (sprinkler, alarm or suppression installs) | 3x to 5x SDE/EBITDA | A written ITM contract book, NICET-certified technicians who stay, AHJ relationships held by staff | CT Acquisitions estimate |
| Regional fire and life safety with a management team, 35-50% recurring revenue | 5x to 8x EBITDA | Recurring revenue above 50%, EBITDA margin above 12-15%, no customer above 15-20% of revenue | CT Acquisitions estimate |
| Platform-scale, 50%+ recurring revenue, multi-state | 8x to 12x+ EBITDA | Professional reporting, licenses in every operating state, route density a buyer can extend | CT Acquisitions estimate |
Public listings sit at the low end. A BizBuySell listing live in October 2026 asked $3.5 million for a fire protection services business reporting $5.0 million in gross revenue and $850,000 in cash flow, roughly 4.1x stated cash flow by the listing’s own figures, in line with the IBBA average for the $2M to $5M band.
Worked example: what a larger inspection book does to price (illustrative)
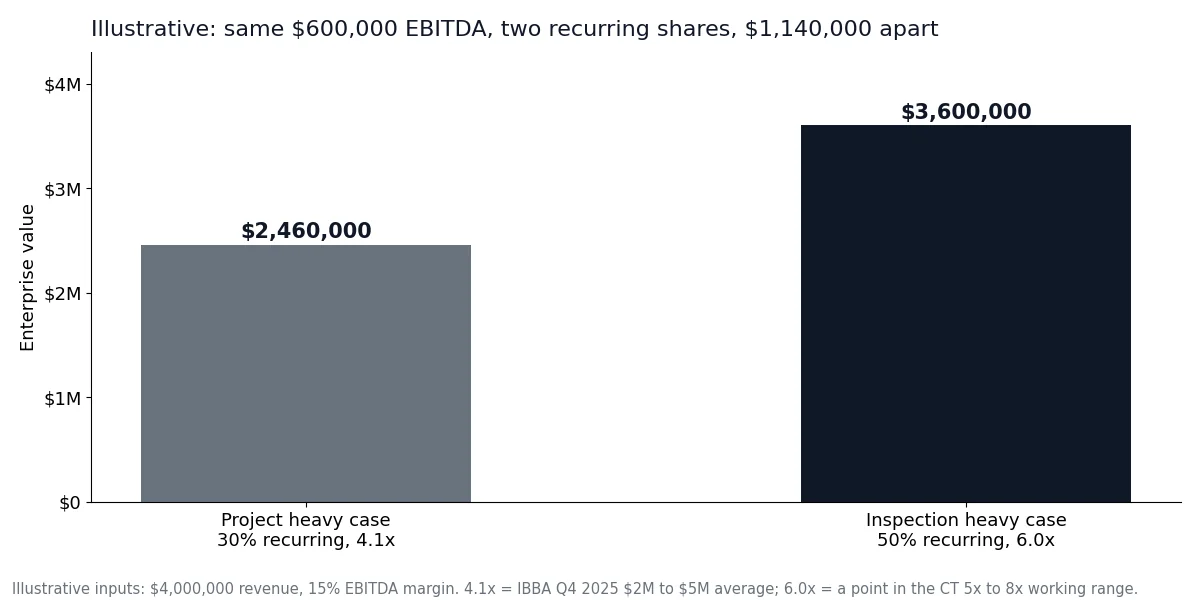
The example below is illustrative, with invented inputs. It holds EBITDA flat at $600,000 and changes only the recurring share, to show how the same earnings can move from the IBBA all-industry average of 4.1x to a CT working-range multiple once half of revenue sits under inspection, testing, maintenance and monitoring contracts.
| Line | Project-heavy case | Inspection-heavy case | How it is calculated |
|---|---|---|---|
| Revenue | $4,000,000 | $4,000,000 | Illustrative input |
| Recurring ITM and monitoring share | 30% | 50% | Illustrative input |
| Recurring revenue | $1,200,000 | $2,000,000 | Revenue x share |
| EBITDA at a 15% margin | $600,000 | $600,000 | Revenue x 15% |
| Multiple applied | 4.1x | 6.0x | IBBA $2M to $5M average vs a point inside the CT 5x to 8x range |
| Enterprise value | $2,460,000 | $3,600,000 | EBITDA x multiple |
| Difference | $1,140,000 | $3,600,000 minus $2,460,000 | |
Why does code-mandated inspection work raise the price?
NFPA standards adopted into state and local fire codes require building owners to buy inspection, testing and maintenance (ITM) on a fixed calendar, so a contract book is revenue a buyer can underwrite. NFPA 25 covers water-based systems, NFPA 72 fire alarms, NFPA 10 portable extinguishers and NFPA 17A wet chemical kitchen systems, with intervals from monthly to 12 years.
The section numbers below come from the Minnesota Department of Health quick-reference guides, revised June 2024, which cite the 2010 and 2011 editions referenced by NFPA 101 (2012) for federal certification. Your state may enforce a later edition, so confirm intervals with the authority having jurisdiction (AHJ) before quoting them to a buyer.
| System and task | Standard and section | Interval | Who typically performs it | Source |
|---|---|---|---|---|
| Sprinkler control valves and wet pipe gauges, visual | NFPA 25 (2011) §5.1.1.2, Table 5.1.1.2 | Monthly | Owner staff | MDH sprinkler guide |
| Mechanical waterflow alarm devices, test | NFPA 25 §5.3.3, §13.2.6 | Quarterly (vane and pressure switch types: semiannually) | Trained staff or contractor | MDH sprinkler guide |
| Annual sprinkler service: main drain test, sprinklers from floor level, hangers, valves | NFPA 25 Table 5.1.1.2, §5.2.1 | Annually | Licensed sprinkler contractor | MDH sprinkler guide |
| Internal pipe inspection, check valves, gauge replacement or test | NFPA 25 §14.2.1, §13.4.2.1, §5.3.2 | Every 5 years | Licensed sprinkler contractor | MDH sprinkler guide |
| Fast-response sprinklers, replace or sample test | NFPA 25 §5.3.1 | At 20 years, then every 10 years | Licensed sprinkler contractor | MDH sprinkler guide |
| Fire alarm components, visual inspection | NFPA 72 (2010) Table 14.3.1 | Semiannually | Owner staff | MDH fire alarm guide |
| Entire fire alarm system, inspect and test | NFPA 72 Tables 14.3.1 and 14.4.5 | Annually | Approved servicing company | MDH fire alarm guide |
| Nonrestorable spot-type heat detectors | NFPA 72 Table 14.4.2.2 | Replace after 15 years | Approved servicing company | MDH fire alarm guide |
| Portable extinguishers, visual inspection | NFPA 10 (2010) §7.2.1 | Monthly (30-day intervals) | Owner staff | MDH extinguisher guide |
| Portable extinguishers, maintenance | NFPA 10 §7.3 | Annually | Trained technician | MDH extinguisher guide |
| Stored-pressure dry chemical extinguishers, internal examination | NFPA 10 §7.3.1.2 | Every 6 years | Trained technician | MDH extinguisher guide |
| Hydrostatic test: water, CO2, wet chemical (K-type) / dry chemical | NFPA 10 §8.3.1, Table 8.3.1 | Every 5 years / every 12 years | Hydrostatic test facility | MDH extinguisher guide |
| Kitchen hood fire-extinguishing system, service | NFPA 96 (2011) §11.2.1 | Every 6 months | Trained, qualified person | MDH kitchen guide |
| Wet chemical kitchen system cylinders, hydrostatic test | NFPA 17A (2009) §7.5.1 | Every 12 years | Trained, qualified person | MDH kitchen guide |
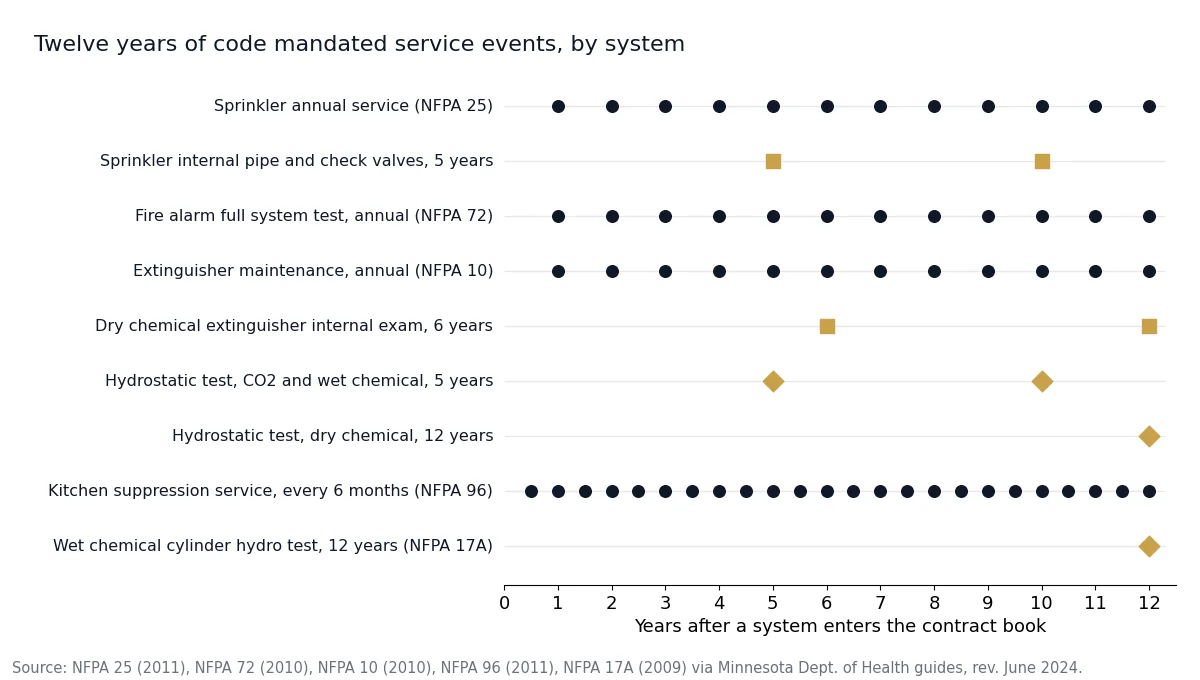
A buyer reading your customer list multiplies each system by its interval. One building with a wet sprinkler system, an alarm panel and 20 extinguishers carries at least one annual sprinkler service under NFPA 25 Table 5.1.1.2, one annual alarm test under NFPA 72 Table 14.4.5 and one annual extinguisher maintenance under NFPA 10 §7.3, plus 5-year and 6-year work already on the calendar. Billed visits below that count are revenue the buyer expects to add, and a sign the contracts are not being renewed.
Kitchen exhaust cleaning is a different asset with different buyers. NFPA 96 Table 11.4 sets hood and duct inspection by cooking volume, and owners whose revenue is mostly cleaning routes should read how to sell a hood cleaning business. Suppression service on the same hood, every 6 months under NFPA 96 §11.2.1, stays with the fire protection company and counts toward its ITM book.
Do fire protection licenses transfer when you sell?
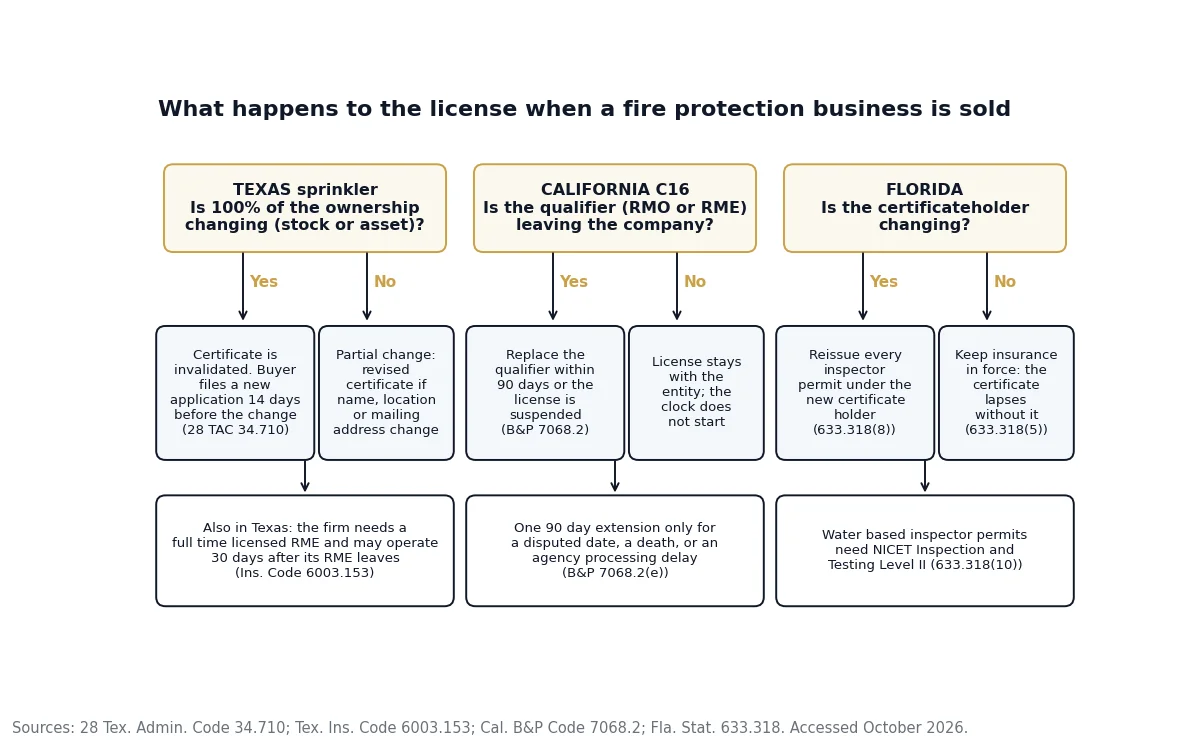
Usually not on their own. Texas makes sprinkler registrations and licenses non-transferable by statute (Texas Insurance Code §6003.160), California ties a contractor license to a named qualifier who must be replaced within 90 days of leaving, and Florida inspector permits are valid only under the certificateholder named on them. Deal structure decides how much re-licensing the buyer faces.
| State and credential | Rule at a sale or staff exit | Deadline | Primary source |
|---|---|---|---|
| Texas: sprinkler certificate of registration (firm) plus responsible managing employee (RME) license (individual) | A total change of the firm’s ownership invalidates the certificate; neither the certificate nor the RME license is transferable; the firm must employ at least one full-time licensed RME | New application 14 days before the change; officer changes and RME departures reported within 14 days; firm may operate 30 days after its RME’s death or dissociation | 28 TAC §34.710, §34.711; Tex. Ins. Code §6003.153, §6003.160 |
| Texas: fire alarm and fire extinguisher work | Licensed under separate chapters (6002 alarms, 6001 extinguishers); hydrostatic testing of extinguishers needs its own registration | Check each credential the company holds | Tex. Ins. Code Chapters 6001 and 6002, §6001.153 |
| California: C-16 Fire Protection Contractor, held through a qualifier (RMO or RME) | C-16 excludes electrical alarm systems; when the qualifier disassociates, the license must get a replacement qualifier; a partnership license is canceled when a general partner leaves | Notify within 90 days; replace within 90 days or automatic suspension; one 90-day extension only for a disputed date, death or agency delay | B&P Code §7068.2, §7076(c); 16 CCR §832.16 |
| Florida: fire protection system contractor certificate (Contractor I to V) | Certificate requires liability insurance of at least $500,000 (Contractor I, II, III, V) or $250,000 (Contractor IV) and does not remain in effect if coverage lapses; inspector permits valid only with the named certificateholder; permit holders need NICET Level II | Re-permit inspectors under the new certificateholder before they inspect | Fla. Stat. §633.318 |
| Florida: fire equipment dealer license (extinguishers, Class A to D) | Permits valid only with the licensee named; one licensed individual may qualify no more than five locations | Count locations per qualifier before closing | Fla. Stat. §633.304 |
Stock sale or asset sale: what changes for the license
A common assumption is that a stock sale keeps every license in place. In Texas the sprinkler rule turns on ownership, not deal form: 28 TAC §34.710(d)(1) says a total change of a firm’s ownership invalidates the current certificate, so a 100% stock sale still needs a new application. A partial change needs only a revised certificate when it alters the firm’s name, location or mailing address.
California’s §7068.2 clock starts when the qualifier leaves, not when shares change hands. If the selling owner is also the qualifying RMO, the buyer needs a replacement qualifier on file within 90 days of the owner’s exit, and a C-16 license cannot be stretched to cover alarm work that 16 CCR §832.16 excludes. In an asset sale, both seller and buyer file IRS Form 8594 to report how the price is allocated under Section 1060 (IRS). Our comparison of stock sale vs asset sale for sellers covers the tax side.
Who buys fire protection companies in 2026?
Four groups buy fire protection companies: national PE-backed platforms such as Pye-Barker Fire & Safety, public strategics such as APi Group, regional operators adding route density, and individual buyers financing with SBA 7(a) loans. Size sets the pool, because the SBA caps a 7(a) loan at $5 million, which leaves larger companies to platforms and strategics.
| Buyer type | Typical target | What they check first | Source |
|---|---|---|---|
| PE-backed national platform (for example Pye-Barker Fire & Safety, 57 acquisitions in 2025) | Regional fire and life safety companies with recurring ITM and monitoring revenue | Contract book, technician retention, state license path | Pye-Barker release, March 17, 2026 |
| Public strategic (APi Group; Johnson Controls, owner of the Tyco and Simplex fire brands) | Inspection-service companies that add density | Inspection volume by standard, AHJ history | Company websites |
| Regional consolidator | Smaller operators in or next to its territory; often closes in 30-90 days below platform multiples | Route overlap, technicians, customer concentration | CT Acquisitions observation |
| Individual operator-buyer | Owner-operated companies, typically under $1-2M EBITDA | SBA eligibility; 7(a) loans top out at $5 million and can fund a change of ownership | SBA 7(a) loans |
If you are comparing advisors rather than buyers, our fire protection M&A advisor guide lists the questions to ask each firm, from deal size handled to the buyers each one can reach.
How do you prepare a fire protection business for sale?
Start 12 to 24 months out. Buyers underwrite three things: the inspection schedule you can prove, the people and licenses that perform it, and clean books that split recurring from project margin. Each step below names the record or threshold a buyer asks for, so the work done now shows up as evidence in diligence instead of as a price cut.
- Export the ITM schedule. One row per system: address, standard (NFPA 25, 72, 10 or 17A), interval, last service date, contract end date. Reconcile billed visits against the intervals in the table above.
- Split revenue three ways for 3 years. Recurring ITM and monitoring, deficiency repair, and project installs, on accrual books with a 2-3 year financial review and documented add-backs.
- Clear the deficiency backlog. Every deficiency an inspection found should show a quote and a completion date; an unquoted backlog reads as lost revenue and open liability.
- Map credentials by technician. NICET Inspection and Testing of Water-Based Systems Level I needs 6 months of experience, Level II 2 years and Level III 5 years (NICET); Florida permit holders need Level II, and a Texas RME-General license needs NICET Water-Based Systems Layout Level III (TDI).
- Retain the 3-5 people who matter. Put key technicians and supervisors on stay bonuses payable at closing, and name who will hold the RME or qualifier role after you leave.
- Write the license path per state. Texas: buyer’s new certificate application 14 days before the change. California: replacement qualifier within 90 days of your exit. Florida: inspector permits reissued under the new certificateholder.
- Cut concentration. Bring any one property manager, general contractor or campus under 15-20% of revenue; our guide on customer concentration and valuation shows how buyers discount it.
- Read every monitoring contract. Confirm assignment clauses and whether a third-party central station agreement ties accounts to your entity; our guide to selling an alarm monitoring company covers how those accounts are valued.
How does the sale process work, step by step?
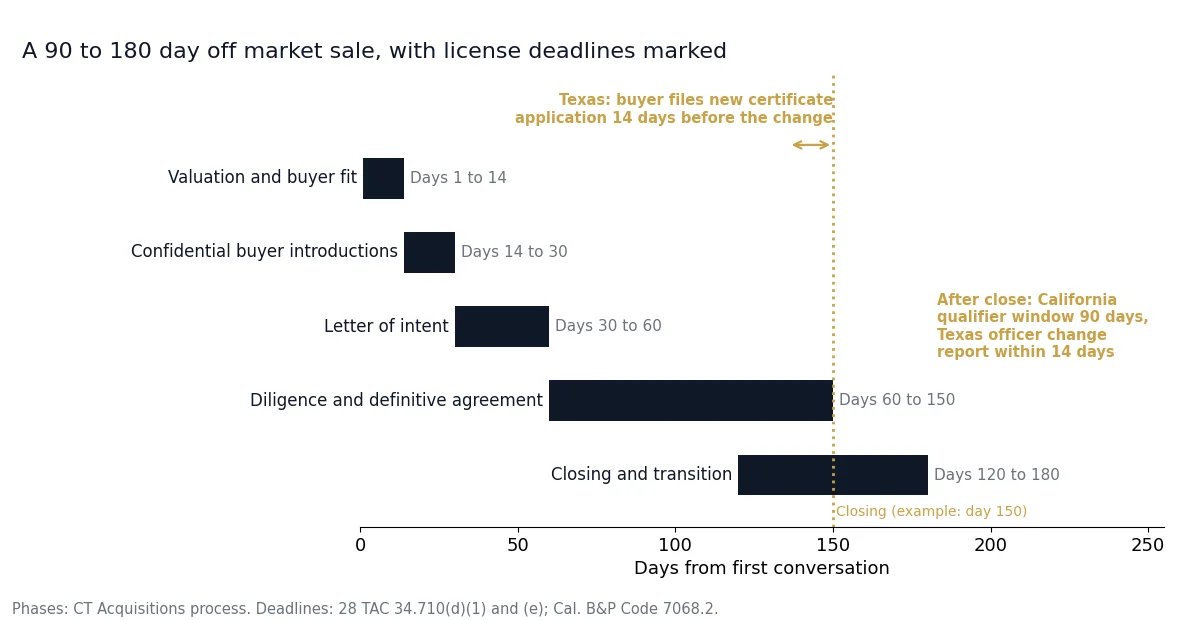
An off-market sale to a PE-backed platform or regional consolidator runs roughly 90-180 days from first conversation to close. License filings run on their own clocks inside that window: in Texas, the buyer’s new sprinkler certificate application is due 14 days before the ownership change, and in California the qualifier replacement window is 90 days from the qualifier’s exit.
| Phase | Days from first call | License and filing actions | Source |
|---|---|---|---|
| Valuation and buyer fit | Days 1-14 | List every state credential and who holds it | CT Acquisitions process |
| Confidential buyer introductions | Days 14-30 | Share the ITM schedule summary, not customer names | CT Acquisitions process |
| Letter of intent | Days 30-60 | Name the post-close RME or qualifier in the LOI | CT Acquisitions process |
| Diligence and definitive agreement | Days 60-150 | Texas: buyer files a new certificate application at least 14 days before closing | 28 TAC §34.710(d)(1) |
| Closing and transition | Days 120-180 | Texas: report officer changes within 14 days; California: replacement qualifier within 90 days of exit; Florida: reissue inspector permits | 28 TAC §34.710(e); B&P §7068.2; Fla. Stat. §633.318(8) |
- Valuation and buyer fit. Agree the earnings basis (SDE or EBITDA) and which buyer groups fit your size.
- Confidential introductions. Buyers see a summary of systems by standard and interval before they see customers.
- Letter of intent. Price, structure (stock or asset), the transition period and who holds each license after closing.
- Diligence. Contract book, deficiency log, NICET levels, insurance certificates, monitoring agreements and the state filings in the table above.
- Closing and transition. Filings land on their statutory deadlines; some buyers tie part of the price to retention through an earnout.
Traditional broker listings for fire protection companies typically take 9-18 months because the public-listing buyer pool is large but unqualified. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing. Our broker alternative guide compares the two routes.
What kills fire protection deals in diligence?
Most fire protection deals that fail or reprice do so over records the seller could have fixed before going to market: a thin or undocumented ITM book, licenses tied to the departing owner, lapsed insurance and customer concentration. Each item below names the consequence a buyer attaches to it, so you can rank the fixes by cost to your price.
- The owner is the only RME or qualifier. In Texas the firm can operate 30 days after its RME dissociates (Tex. Ins. Code §6003.153(c)); without a named successor, the buyer prices that gap.
- Insurance lapsed at any point. A Florida certificate does not remain in effect without the required coverage (Fla. Stat. §633.318(5)).
- One customer above 20% of revenue. Buyers discount the price or shift part of it into an earnout.
- Project-heavy revenue with no ITM contract book. The deal gets priced on SDE at the bottom of the range.
- Technicians paid as 1099 contractors. Worker classification becomes an indemnity item in the purchase agreement.
- Open warranty claims or AHJ disputes on past installs. These move into escrow or holdbacks.
- Leased vs owned equipment not documented. Undisclosed equipment loans reduce cash at close.
Which exit route fits your fire protection company?
Match the route to your size, your recurring share and who holds the licenses. The decision table below pairs each common situation with the step to take first and the rule behind it, using the SBA loan cap, the Texas and California license deadlines and the CT working ranges set out earlier on this page.
| If your situation is | Do this first | Why |
|---|---|---|
| If the price is likely under $5 million and you run the company yourself | Talk to regional consolidators and SBA-financed individual buyers | An SBA 7(a) loan tops out at $5 million (SBA) |
| If recurring ITM and monitoring revenue is above 50% and a management team runs operations | Run a competitive process with PE-backed platforms | That profile sits in the CT 5x to 8x and 8x to 12x+ working ranges |
| If you hold the Texas RME license yourself | Hire or promote a licensed RME before signing | The firm has 30 days after RME dissociation (Tex. Ins. Code §6003.153(c)) |
| If you are the California qualifier | Agree in the LOI how long you stay as qualifier | Replacement is due within 90 days of your exit (B&P §7068.2) |
| If most revenue is kitchen exhaust cleaning | Approach hood cleaning buyers instead | NFPA 96 Table 11.4 cleaning routes draw a different buyer pool |
| If you want to sell only the inspection or monitoring contracts | Check assignment clauses, then sell the book as an asset sale | Both sides file IRS Form 8594 under Section 1060 |
Owners ready to compare offers can go straight to our page to sell your fire protection business with a confidential process.
How we compiled this
We compiled this page from 20 primary documents accessed in October 2026: Texas, California and Florida statutes and rules, four Minnesota Department of Health guides that cite NFPA 10, 25, 72, 96 and 17A section numbers, NICET certification requirements, the IBBA and M&A Source Q4 2025 Market Pulse, SBA and IRS guidance and a Pye-Barker release, plus one BizBuySell listing carried over from the previous version of this page. NFPA texts are paywalled, so section numbers come from the state guides. We excluded forum anecdotes and industry multiples we could not trace to a primary source.
Frequently asked questions
How long does it take to sell a fire protection business?
Off-market sales to PE-backed fire and life safety platforms or regional consolidators typically take 90-180 days from first conversation to close, while traditional broker listings typically take 9-18 months. License filings add fixed steps inside that window, such as the Texas rule that a buyer’s new sprinkler certificate application goes in 14 days before the ownership change (28 TAC §34.710).
Do fire protection licenses transfer to a buyer?
Usually not automatically. Texas Insurance Code §6003.160 makes sprinkler registrations and licenses non-transferable, and a total ownership change invalidates the certificate. California requires a replacement qualifier within 90 days of the old one leaving (B&P §7068.2). Florida inspector permits are valid only under the certificateholder named on them (Fla. Stat. §633.318(8)).
Do you need a license to sell or service fire extinguishers?
Servicing usually needs one. Florida issues Class A to D fire equipment dealer licenses that define which extinguishers a firm may service, recharge or hydrostatically test (Fla. Stat. §633.304). Texas licenses extinguisher work under Insurance Code Chapter 6001 and requires a separate registration to hydrostatically test extinguishers (§6001.153). Check your state fire marshal’s rules before buying or selling an extinguisher route.
Who is the biggest fire protection company?
In the US, the largest fire protection service providers include APi Group, a public company with a large safety services business, and Johnson Controls, which owns the Tyco and Simplex fire brands. Among PE-backed consolidators, Pye-Barker Fire & Safety reported 57 acquisitions in 2025 and 9,000 team members across 47 states in its March 17, 2026 release.
Can I sell just my inspection and monitoring contracts?
Sometimes. Some buyers acquire a book of monitoring accounts or inspection contracts without the rest of the company, usually as an asset sale in which both sides file IRS Form 8594. Check first whether each customer contract allows assignment and whether a central station agreement ties the accounts to your entity. A full company sale usually pays more because the buyer also gets the technicians.
What happens to my technicians when I sell?
Most buyers want to keep them, because certified labor performs the code-mandated work. In Florida, a water-based inspector’s permit is tied to the certificateholder named on it, so permits are reissued under a new certificateholder (Fla. Stat. §633.318(8)). Put your key 3-5 technicians and supervisors on stay bonuses before going to market, since buyers ask for proof they will stay.
Do I need a business broker to sell my fire protection business?
Not necessarily. Smaller owner-operated companies under the $5 million SBA 7(a) loan cap often sell through a broker to individual buyers, while companies with large inspection books usually sell directly to platforms through an advisor. With CT Acquisitions: no fee to you on buy-side introductions; sell-side mandates are paid on success at closing.
Sources
- 28 Tex. Admin. Code §34.710, Certificates of Registration (accessed October 2026)
- 28 Tex. Admin. Code §34.711, RME License (accessed October 2026)
- Texas Insurance Code Chapter 6003, §6003.153 and §6003.160 (accessed October 2026)
- Texas Insurance Code Chapter 6001, §6001.153 (accessed October 2026)
- Texas Department of Insurance, fire sprinkler registration, license and test information (accessed October 2026)
- California Business and Professions Code §7068.2 and §7076 (accessed October 2026)
- 16 CCR §832.16, Class C-16 Fire Protection Contractor (accessed October 2026)
- Florida Statutes §633.318 and §633.304 (accessed October 2026)
- Minnesota Department of Health, sprinkler ITM guide (rev. June 2024) (accessed October 2026)
- Minnesota Department of Health, fire alarm testing guide (rev. June 2024) (accessed October 2026)
- Minnesota Department of Health, portable fire extinguisher guide (rev. June 2024) (accessed October 2026)
- Minnesota Department of Health, kitchen cooking equipment guide (rev. June 2024) (accessed October 2026)
- NICET, Inspection and Testing of Water-Based Systems certification requirements (accessed October 2026)
- IBBA and M&A Source, Market Pulse Q4 2025 Highlights (accessed October 2026)
- U.S. Small Business Administration, 7(a) loans (accessed October 2026)
- IRS, About Form 8594 (accessed October 2026)
- Pye-Barker Fire & Safety release, March 17, 2026 (accessed October 2026)
Fire Protection Valuation
What’s your fire protection business worth?
Get a sector-adjusted multiple range using current 2026 fire and life safety transactions. We apply fire-protection-specific adjustments for recurring ITM revenue, monitoring base, multi-year contract percentage, technician certification, and AHJ relationships.
Get a Fire Protection Valuation →Curious what your business is worth?
A 15-minute confidential call gives you a real valuation range and tells you which buyers would compete for your business. No cost, no obligation, no pressure to sell.
The five pillars of how CT Acquisitions works
Sell side for owners, buy side for acquirers, plus exit planning.
No fee on buy-side introductions. Sell side paid on success.
Search funders, family offices, lower-middle-market PE, strategics.
Introductions to the right buyers only. No public listing.
Not 9-18 months. Months, not years.
No Pitch · No Pressure
Considering selling your fire protection business?
Tell us about your business, recurring vs project mix, ITM contract base, region, size. We have buyers actively acquiring fire protection businesses, and we’ll discuss what yours is worth, which buyers fit, and what to expect. No obligation to proceed after the first conversation.
Start a Confidential Conversation →
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm working both sides of the table, headquartered in Sheridan, Wyoming. We work directly with 500+ buyers, search funders, family offices, lower middle-market PE, and strategic consolidators, including direct mandates with the largest consolidators that other intermediaries cannot access. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing. Connect on LinkedIn · Get in touch
Related research
- Free Business Valuation Tool, your business is worth in 90 seconds
- The Business Broker Alternative Guide (national pillar)
- Business Brokers by State, with a confidential alternative
- The Complete Guide to Selling Your Business in 2026
- What’s My Business Worth? Founder’s Valuation Guide
- Who Buys These Companies? Buyer Types Explained
- How to Sell to Private Equity, A Founder’s Walkthrough
- Owner’s Pre-Exit Checklist, 90 Days Before You List
- CT Commentary, Founder & M&A Insights
